• Mon - Fri 9.00 - 19.00

Tag Archives: central banks

Everyone Around Switzerland Is Raising Rates. It Just Sat Still

The Swiss National Bank left its policy rate at 0% on Thursday, 24 September 2026. The Swiss National
Bank decision
stands out because its neighbours went the other way. In its own statement, the SNB noted
that key rates were raised both in the euro area and in the US. Switzerland can afford to wait, for now,
because its inflation remains low.

What the Swiss National Bank decision kept in place

The policy rate stays at 0%. Banks’ sight deposits at the SNB earn that rate up to a threshold. Above
it, the discount remains 0.25 percentage points. The bank also repeated that it is willing to act in the
foreign exchange market as necessary. Those details come from the
SNB’s monetary policy assessment.

The SNB called its stance "appropriate" to keep inflation within the range it defines as price
stability. That range is 0% to 2%.
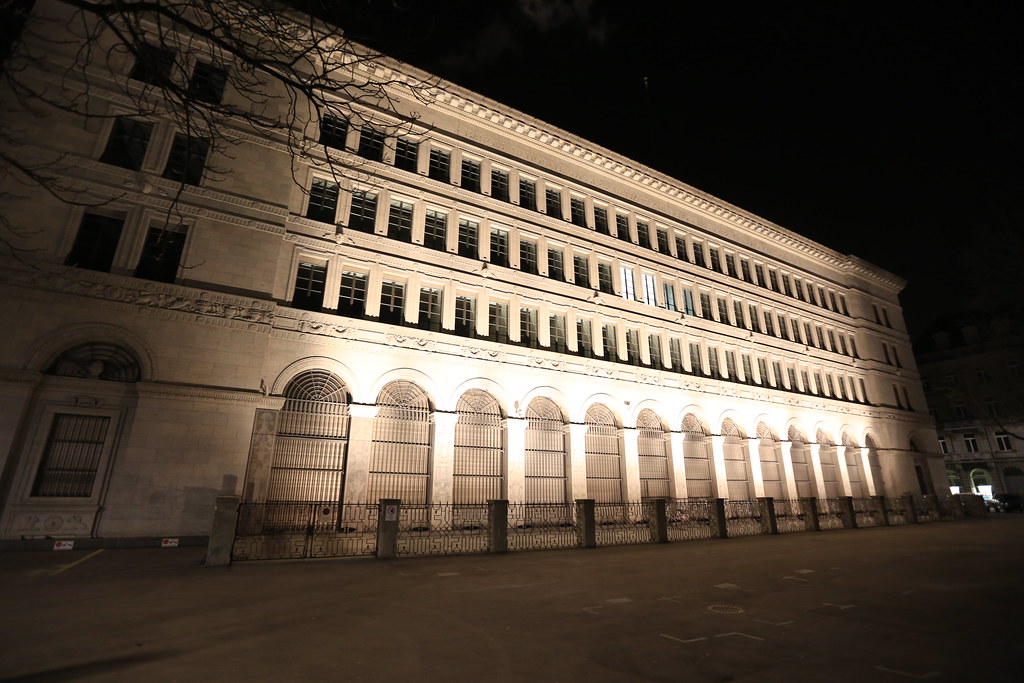
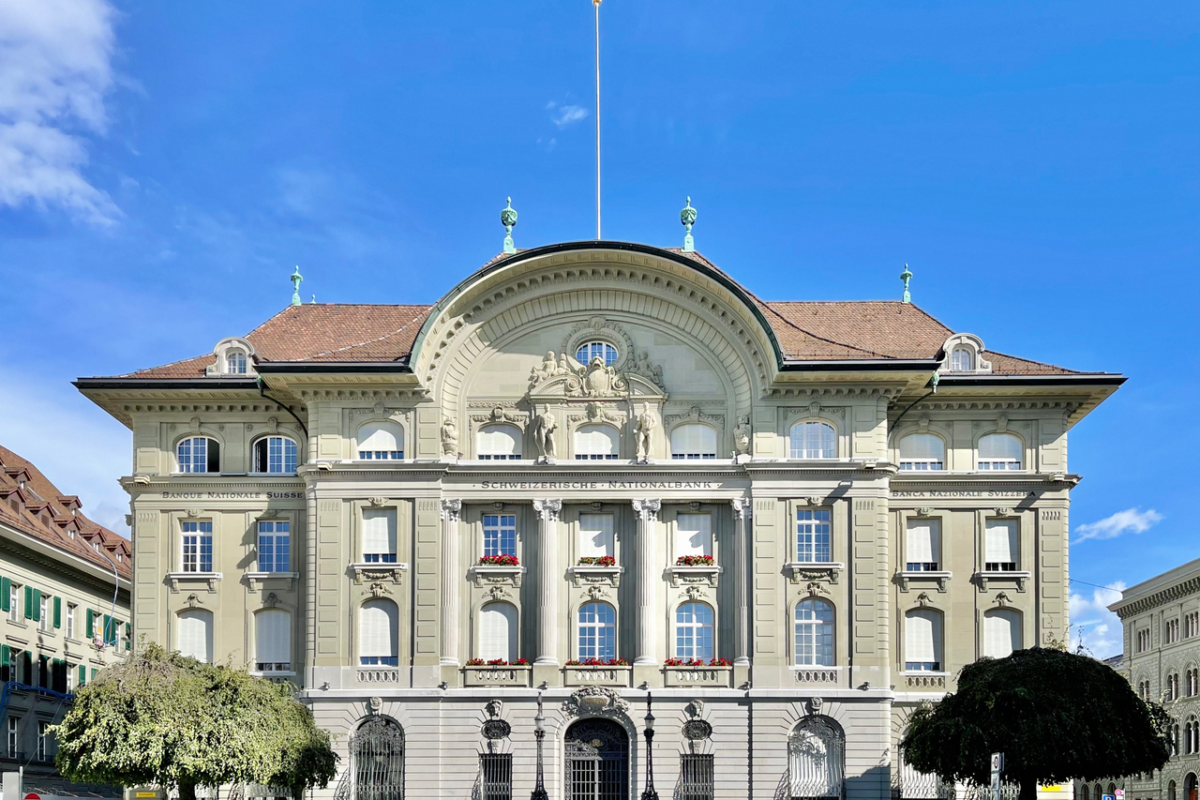
Swiss National Bank office in Zurich, one of the two seats behind the Swiss National Bank decision
The SNB runs head offices in Bern and Zurich.

The inflation picture behind the hold

Prices are rising, just slowly. Swiss inflation climbed from 0.6% in May to 0.8% in August. Goods
inflation turned positive in August for the first time since May 2024. Higher prices for oil products
drove most of that move.

The SNB expects inflation to rise a little further in the fourth quarter. It then sees it easing
during 2027 as energy inflation fades. Its conditional forecast reads:

  • 2026: 0.7% average inflation
  • 2027: 0.8%
  • 2028: 0.8%

That path stays inside the target band throughout. It assumes the policy rate holds at 0% over the
whole horizon. The bank said the medium-term forecast edged up partly because the Swiss franc has
weakened.

Why the Swiss National Bank decision diverges from the Fed and ECB

The contrast with other big central banks is the story. The US Federal Reserve raised its target range
to 3.75%-4.00% in September, its first hike since 2023, as CNBC reported.
Our coverage of the Fed’s rate hike explains
what drove that vote. The European Central Bank also tightened, as set out in our report on the
ECB interest rate hike.

Both face inflation above their 2% goals, much of it tied to energy. Switzerland does not. Its inflation
sits well below 1%. That gives the SNB room to hold while others squeeze.

A weaker franc helps the Swiss economy in the short run. The SNB said the recent depreciation is
having a supportive effect on growth.

The global backdrop matters here. The SNB noted that key rates rose in both the euro area and the US,
while inflation in many countries stayed above target on higher energy prices. Its own base case sees
moderate global growth ahead. It also sees inflation staying elevated for some time. That external picture
shapes how long Switzerland can keep its own rate at zero.

What the SNB expects for the Swiss economy

Second-quarter GDP growth was exceptionally strong. The SNB said an unusual surge in chemicals and
pharmaceuticals overstated the underlying pace. Even without it, growth was solid and broad-based.

There are soft spots. Capacity use sat below average, especially in manufacturing. Unemployment rose
again somewhat through early summer. The bank now expects growth of 1.5% to 2% for 2026, and around 1.5%
for 2027.

Where Swiss rates go from here

The SNB flagged the Middle East as the biggest risk. If energy prices end up significantly higher,
inflation would rise and growth would slow. Trade policy and exchange rates remain further sources of
uncertainty.

For savers and borrowers in Switzerland, little changes today. Mortgage and deposit rates tied to the
policy rate should stay near current levels. For currency watchers, the key variable is the franc. A much
weaker franc would push imported inflation up and test the 0% setting. The SNB holds its assessments
quarterly, so the next scheduled decision falls in December.

Swiss rate questions, answered

What did the Swiss National Bank decide?

On 24 September 2026 the SNB left its policy rate unchanged at 0%. The discount on sight deposits above the exemption threshold also stayed at 0.25 percentage points.

Why did the SNB hold while other central banks raised rates?

Swiss inflation is still inside the SNB’s 0-2% target range. It stood at 0.8% in August. The US Federal Reserve and the European Central Bank face inflation above target, which pushed them to hike.

What is the SNB’s inflation forecast?

The conditional forecast puts average inflation at 0.7% for 2026, 0.8% for 2027 and 0.8% for 2028. It assumes the policy rate stays at 0% throughout.

Will the SNB intervene in currency markets?

The SNB said it remains willing to be active in the foreign exchange market as necessary. It did not say whether it has intervened recently.

How fast is the Swiss economy growing?

The SNB expects growth of 1.5% to 2% in 2026 and around 1.5% in 2027. It said strong second-quarter GDP partly reflected an unusual boost from chemicals and pharmaceuticals.

What is the main risk the SNB flagged?

The situation in the Middle East. The SNB warned that energy prices could turn out significantly higher than expected, which would raise inflation and curb growth.

Sources

  • Swiss National Bank — Monetary policy assessment of 24 September 2026. snb.ch
  • CNBC — Fed rate decision September 2026: Rates rise to 3.75%-4%. cnbc.com

Images: featured photo by Robbie Conceptuel (CC0); in-article photo by TravelingOtter, licensed CC BY.
Japan’s Rates Just Hit a 31-Year High — But the Yen Fell Anyway

The Bank of Japan rate hike landed on Friday, September 18, 2026, lifting the country’s benchmark borrowing cost to 1.25%. That is the highest level since 1995, a full 31-year high. The board voted 7-2 for the increase, and two members pushed to hold steady instead. Governor Kazuo Ueda said the bank will not commit to a fixed pace for future moves. He signaled further hikes could follow if inflation risks keep building. The decision lands as central banks worldwide tighten policy together, from Washington to Frankfurt.

The Bank of Japan Rate Hike Pushes Borrowing Costs to a 31-Year High

The BOJ raised its key overnight rate by 25 basis points, from 1.00% to 1.25%. The increase came three months after the bank’s last hike in June. That gap is shorter than the six-month intervals the BOJ used earlier in its tightening cycle, according to UPI. The bank has been raising rates since it ended negative interest rates and large-scale easing in March 2024. Japan’s core consumer price index, which excludes fresh food, rose 1.7% in August from a year earlier. That sits just under the BOJ’s 2% target, but policymakers worry it could overshoot.

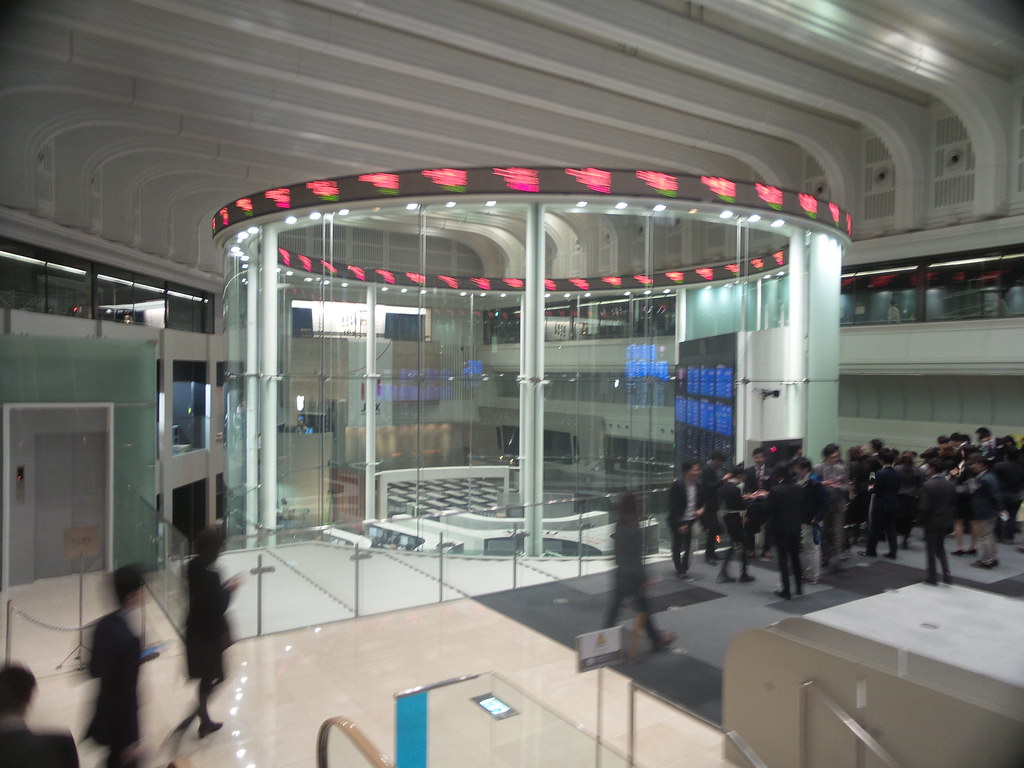
Bank of Japan rate hike: Tokyo financial district skyline at dusk

A Divided Board: Why Two Policymakers Opposed the Rate Hike

Board members Toichiro Asada and Ayano Sato dissented from the hike. Both argued the bank should wait. Asada has said core inflation still sits below 2%, so a further tightening move looked premature to him. Prime Minister Sanae Takaichi appointed both dissenters to the board. Her government favors expansive fiscal policy, including a cut to the consumption tax on food, which sits in tension with the BOJ’s tightening path. That split vote mattered to markets. It signaled the board is not unified behind a fast tightening pace, even as Governor Ueda kept the door open to more increases.

Market Reaction to the Rate Hike: Yen, Nikkei, and Bond Yields

Higher rates usually lift a currency by drawing in yield-seeking money. This time, the yen fell instead. USD/JPY pushed back above 157 after the announcement. Traders had wanted a clearer signal on future hikes and did not get one from the 7-2 split or from Ueda’s cautious tone. The Nikkei 225 rose about 1.5% on the day, while the 10-year Japanese government bond yield eased back after climbing toward three-decade highs in recent weeks. The yen’s weakness is not new this year. It slid to nearly 164 per dollar in July, close to a 40-year low, prompting Japan to spend a record 15.4 trillion yen buying its own currency between July 30 and August 26. The United States and South Korea joined that intervention effort, a rare instance of coordinated currency support among the three economies.

A Global Rate-Hike Wave: the Fed and ECB Also Tightened

The Bank of Japan rate hike did not happen in isolation. The U.S. Federal Reserve raised its own benchmark rate by 25 basis points on September 16, its first increase since 2023. The European Central Bank moved even earlier, lifting its deposit rate by 25 basis points on September 10 to 2.50%. All three institutions point to the same pressure: oil prices climbing on the back of the conflict in the Middle East, which has pushed inflation above target across major economies. Resource-poor Japan imports nearly all its energy, so it feels that shock directly. The synchronized tightening has also kept government borrowing costs elevated worldwide, a trend visible in the recent climb in U.S. Treasury yields and in Japan’s own 10-year bond. The ECB’s September increase marked its second hike since the war began and, according to a Reuters poll, likely its last for now.

Where Japan’s Interest Rates Go From Here

Ueda gave few hints about the exact timing of the next move. “We don’t have any pre-set idea in mind such as once every three months,” he told reporters after the meeting, according to Reuters. He added that the bank would decide meeting by meeting whether underlying inflation was stabilizing near 2%. Asked whether the BOJ might deliver a bigger or back-to-back increase, he said, “There could be various possibilities. We shouldn’t rule anything out.” U.S. Treasury Secretary Scott Bessent has also pressed Tokyo to normalize policy faster and support the yen, adding external pressure to the BOJ’s own inflation math. The bank’s next policy meeting runs October 29-30, when it will publish a fresh quarterly Outlook Report with updated growth and inflation forecasts. Analysts will watch wage negotiations and oil prices closely between now and then, since both feed directly into the BOJ’s inflation outlook. Some traders also flagged that a slide toward 160 yen per dollar could invite fresh government intervention to defend the currency.

Frequently Asked Questions About the Bank of Japan Rate Hike

What did the Bank of Japan decide on September 18, 2026?
The BOJ raised its policy rate by 25 basis points to 1.25%, the highest level since 1995. The board voted 7-2 in favor of the increase.

How big was the Bank of Japan rate hike?
The hike moved the benchmark rate from 1.00% to 1.25%, a quarter-point increase. It was the BOJ’s first hike since June 2026.

Why did the yen fall after the Bank of Japan raised rates?
The yen weakened because the board’s split vote and Governor Ueda’s cautious comments suggested the BOJ is in no rush to hike again soon. A wide interest-rate gap with the United States also keeps pressure on the currency.

How does the Bank of Japan rate hike compare with the Fed and ECB?
All three central banks raised rates within days of each other in September 2026, citing inflation pressure tied to rising oil prices from the Middle East conflict. The Fed hiked on September 16 and the ECB on September 10.

Will the Bank of Japan raise rates again?
Governor Ueda has not ruled out further increases but declined to commit to a fixed schedule. The bank’s next meeting, on October 29-30, will include updated inflation forecasts.

What is Japan’s core inflation rate now?
Core consumer prices, excluding fresh food, rose 1.7% year-on-year in August 2026, just under the BOJ’s 2% target.

Sources

The Asia Oil Price Shock Lands on Economies With No Room

Brent crude has pushed back above $100 a barrel, and the Asia oil price shock is landing on economies that have almost no policy room left to absorb it. Japan, South Korea and India import the bulk of the crude that powers their industry. Indonesia and Thailand subsidise fuel, which converts a market price into a budget line.

Bloomberg framed it as a fresh test of the region’s resilience, arriving with inflation already running hot and both fiscal and monetary policy already tight.

Two different problems wearing the same clothes

Dearer oil hits Asian economies through two separate channels, and conflating them produces bad forecasts.

For import-dependent manufacturers — Japan, South Korea, and to a large extent India — the cost arrives as an input price. It widens the trade deficit, pressures the currency, and works through to consumer prices over one to two quarters. Central banks can respond, at the cost of growth.

For fuel subsidisers — Indonesia, Thailand and others — the cost arrives as a fiscal transfer. The government absorbs the gap between world price and pump price, so consumer inflation stays contained while the deficit widens. The pressure shows up in bond markets rather than CPI, and the political cost of removing a subsidy mid-shock is prohibitive.

Both are painful. They call for opposite responses, which is why a regional generalisation about “Asia” tends to mislead.

Why the market reaction has been calmer than the number suggests

Triple-digit oil used to reliably trigger growth scares. This time the reaction has been comparatively muted.

The reason offered by analysts is that investors read the move as a supply constraint driven by conflict rather than a demand-side energy crisis — a bounded, geopolitical premium rather than a structural repricing. Discussion of that reading appeared in market commentary following the move.

That reading holds only as long as the supply disruption stays bounded. It is worth noting the assumption explicitly, because it is doing a lot of work.

It is already in the data

This is no longer a forecast. US wholesale prices rose 0.4% in August, driven by energy — the release we covered in detail here. Elevated crude and refined product prices feed consumer indices with a lag, and Asian economies with higher energy weightings in their baskets will see it sooner than the US does.

The awkward part is the sequencing. The European Central Bank has already moved, raising rates in September, and the Federal Reserve meets on 16 September with markets leaning toward a hike, as set out in our preview. Asian central banks that follow face tightening into an oil-driven slowdown. Those that do not face currency pressure that makes imported energy still more expensive in local terms.

The subsidy arithmetic

For governments capping pump prices, the cost scales directly with both the crude price and consumption volume, and neither falls quickly.

Three imperfect options exist. Absorb the cost and widen the deficit. Pass some through and accept the inflation and the politics. Or narrow eligibility so support reaches lower-income households only — cleanest in theory, slow to implement, and dependent on transfer systems not every country has.

Most governments will default to absorbing it in the short run, which means the fiscal damage accumulates quietly and shows up later in borrowing costs.

India sits awkwardly between the two categories. It imports the large majority of its crude, which gives it the input-cost problem, and it retains politically sensitive fuel pricing, which gives it a version of the fiscal one. Japan and South Korea, by contrast, pass energy costs through more directly, so the pain appears faster in their inflation prints and more visibly in industrial margins.

Indicators worth tracking

  • Currency moves against the dollar. A weakening currency multiplies the local-currency cost of crude and is the fastest transmission channel.
  • Fuel subsidy announcements. Any adjustment to capped prices signals that a government has decided it can no longer absorb the gap.
  • Central bank commentary on “second-round effects”. That phrase is the tell that a bank has stopped treating the shock as temporary.

Questions on the oil shock

How high has oil actually gone?

Brent traded above $107 a barrel, having crossed $100 for the first time in months. Prices closed the week more than 8% higher.

Which Asian economies are most exposed?

Japan, South Korea and India through import dependence for industry; Indonesia and Thailand through the fiscal cost of fuel subsidies. The exposure differs in kind, not just degree.

Why has the market reaction been relatively muted?

Analysts attribute it to investors reading the rise as a conflict-driven supply constraint rather than a broad energy crisis. That interpretation depends on the disruption remaining contained.

Will this force Asian central banks to raise rates?

Not automatically. Standard practice is to look through supply-driven price rises, but that is harder when inflation is already above target. Watch for language about second-round effects.

How does a fuel subsidy change the picture?

It moves the cost from consumers to the government budget. Consumer inflation stays lower, the fiscal deficit widens, and the strain appears in bond markets instead of price indices.

How quickly does crude reach consumer prices?

Typically one to two quarters for the full pass-through, though fuel and transport costs move faster. Economies with higher energy weightings in their consumer baskets see it sooner.

We are tracking the central bank response across regions — see our coverage of the ECB’s September move.

The Bank of England’s Next Vote Could Go Either Way. Here’s the Math

The next Bank of England September vote lands on Thursday, September 17, 2026, at noon London time. It follows a divided vote in July, when three of nine Monetary Policy Committee members wanted a rise to 4.00% while the majority held Bank Rate at 3.75%. That split leaves the September outcome unusually hard to call.

Why the Bank of England September vote is finely balanced

Headline UK inflation has risen from 2.6% to 2.9% since the July meeting, according to the Bank’s own July 2026 monetary policy summary. The Bank’s central projection at that meeting showed CPI inflation peaking around 3.2% in the fourth quarter of 2026, well above the 2% target.

Bank of England September vote
The Bank of England's Next Vote Could Go Either Way. Here's

Crucially, August inflation figures land at 7am on Wednesday, September 16, the morning before the Committee votes. That means members will have two additional Consumer Prices Index readings and two more labour market releases in hand compared with the July meeting, giving fresher data a real chance to move the outcome.

What markets are pricing in

Market-implied probability estimates have varied notably in recent days. Some readings put the probability of no change as high as 90%, while earlier estimates put it closer to 72%, according to analysis from BritSavvy. A market-implied move of roughly 7 basis points above the current 3.75% rate suggests traders see some, but not overwhelming, chance of a hike.

The spread between those estimates itself signals genuine uncertainty. Unlike meetings where a hold or hike is treated as close to certain going in, this decision remains open heading into the final data releases.

The case for holding versus hiking

Policymakers favoring a hold point to the risk that raising rates too aggressively could choke off growth just as inflation pressures show signs of moderating elsewhere in the economy. Those favoring a rise argue that inflation running nearly a full point above target, and rising rather than falling, justifies tighter policy now rather than waiting.

The three dissenting votes in July signal that at least a meaningful minority of the Committee already leans toward tightening. Whether that minority grows depends heavily on what the August inflation print shows.

What to watch before the September vote

The August CPI release on September 16 is the single data point most likely to shift expectations. A reading meaningfully above 2.9% would strengthen the case for a hike. A reading that holds steady or eases would support the majority’s preference to hold.

Labour market data due before the meeting will also factor into the Committee’s thinking. Wage pressure remains a key input into how persistent inflation is likely to prove over the coming year.

Mortgage holders and homebuyers have a direct stake in the outcome too. A hold keeps borrowing costs steady for now, while a surprise hike would raise monthly payments on new and variable-rate mortgages almost immediately.

How this compares with the Fed and ECB

The Bank of England is not alone in facing a close call this month. The U.S. Federal Reserve left rates unchanged for a fifth straight meeting in July, though three officials dissented in favor of a hike. Fed Chair Kevin Warsh flagged persistent underlying inflation at the Jackson Hole symposium in August.

The European Central Bank, by contrast, has held its key rates steady since July with less internal division. Eurosystem staff project headline inflation averaging 3.0% in 2026, broadly similar to the Bank of England’s own outlook.

What sets the UK apart is the size of the dissent. A 6-3 vote signals real disagreement within the Committee, more pronounced than the splits currently visible at the Fed or ECB. That makes the Bank of England September vote this month one of the more closely watched among major central banks.

Currency traders have taken note. Sterling has shown more sensitivity to incoming UK data releases in recent weeks than the dollar or euro have to their own domestic releases, reflecting the market’s uncertainty about which way the September vote will go.

Readers’ questions on the rate decision

When is the next Bank of England September vote?
The Monetary Policy Committee announces its decision on Thursday, September 17, 2026, at noon London time.

What was the outcome of the July meeting?
The Bank held Bank Rate at 3.75% in a divided 6-3 vote, with three members preferring a rise to 4.00%.

What is UK inflation running at now?
Headline CPI inflation has risen from 2.6% to 2.9% since the July decision, with the Bank projecting a peak near 3.2% in Q4 2026.

What data comes out before the decision?
August inflation figures are released at 7am on September 16, the morning before the vote, along with additional labour market data.

Are markets expecting a rate hike?
Estimates vary. Some market-implied probabilities put the chance of no change as high as 90%, while other readings suggest a closer contest.

For related central bank coverage, see our reporting on the Bank of Canada’s rate hold and the latest jobs report and rate-hike odds.

Sources