• Mon - Fri 9.00 - 19.00

Tag Archives: inflation

Gulf Drivers Pay 60% More at the Pump, Relief Isn’t Near

The Gulf oil price shock is not easing, even as officials insist the Strait of Hormuz is functioning again. Pump prices in the UAE rose for a third straight month in October, war-risk insurance premiums keep climbing, and the IMF is warning that relief may not come quickly. The economics of the Gulf war have become a story of their own, separate from who controls the water.

Inside the Gulf Oil Price Shock at the Pump
Gulf oil price shock

The UAE’s Fuel Price Committee raised retail prices for October, the third consecutive monthly increase. Super 98 petrol rose to Dh4.40 a litre from Dh3.80. Diesel climbed to Dh4.80 a litre from Dh4.30, according to Gulf News. Retail fuel prices in the UAE have now risen more than 60 per cent since the war began in late February.

A typical 50 to 60 litre fill-up now costs up to Dh125 more than before the spike. The G7 released 100 million barrels from emergency stockpiles earlier in the year, a move that briefly cut prices by roughly $5 a barrel. October’s pump prices still reflect the spike that move only partly offset.

Why the Gulf Oil Price Shock Is Proving Sticky

Crude is technically moving again. Ship-tracker Kpler put the seven-day average for Gulf crude exports at 18.5 million barrels per day on October 1, against a pre-war average near 18 million bpd, per Khaleej Times. Combined crude, products and other liquids reached 22.4 million bpd in the week to September 30.

Volume recovering does not mean costs are back to normal. Insurers are charging higher war-risk premiums for Gulf transit, and that raises freight rates and import costs further down the chain. Shipping intelligence firm Marisks tracked at least seven tanker incidents around the strait in recent weeks, including an October 1 fire on the crude carrier Kazimah III. The UK’s maritime trade agency has logged at least one attack a day in the strait or the Gulf of Aden since October 2, which keeps insurers cautious even as tonnage flows.

The IMF’s Warning on Oil Prices Clashes With Washington’s Optimism

US officials have struck an upbeat tone. Secretary of State Marco Rubio said this week that oil flows are nearly back to prewar levels and that the strait is open. IMF managing director Kristalina Georgieva offered a more cautious note. Speaking in Singapore ahead of the fund’s annual meetings, she said: “Even if the war in the Gulf were to end soon, the problem of high energy prices would likely persist for some time,” The National reported. She described the energy shock as large but contained.

Not every voice sounds pessimistic. Vitol’s Tom Baker said Gulf refining capacity is recovering quickly, helped by roughly 2 million bpd of Russian refining capacity that remains offline and reduced Chinese output, both of which keep demand for Gulf barrels firm regardless of the politics.

What Could Ease the Gulf Oil Price Shock Next

Three things will decide whether the Gulf oil price shock eases or deepens. First, whether tanker attacks slow down enough for insurers to cut war-risk premiums. Second, whether the diplomatic track Rubio and Vance described produces an actual enrichment deal, not just another truce. Third, whether Asian and European buyers keep paying a premium for Gulf cargoes instead of switching suppliers.

None of those answers will arrive this week. The squeeze adds to a week already crowded with economic news, from bank earnings season to mortgage rates sitting at a three-year high and a September jobs report that missed estimates, all feeding into how central banks read the inflation outlook.

For now, households and shippers absorbing the costs are the clearest sign that a dispute over a waterway has become an ordinary economic burden.

Gulf Oil Price Shock: Questions Worth Asking

Why are fuel prices still rising if oil exports have recovered?
Export volumes and retail prices move separately. Insurance costs, refining disruptions elsewhere and cautious shipping all keep landed costs higher even when tanker traffic resumes.

How much have UAE pump prices risen since the war began?
More than 60 per cent since late February 2026, according to Gulf News, with the Fuel Price Committee raising prices for a third straight month in October.

Does the IMF expect prices to fall soon?
No. Kristalina Georgieva said high energy prices could persist even if the war ends soon, calling the shock large but contained rather than temporary.

Are oil exports really back to pre-war levels?
Kpler’s tracking puts exports close to or slightly above pre-war averages, though Iran’s IRGC disputes this and tanker attacks keep threatening the recovery.

Who is most exposed to rising war-risk insurance costs?
Shippers and airlines operating in or near the Gulf, which pass higher premiums on to freight rates, ticket prices and ultimately consumer goods.

What would actually bring prices down?
A durable drop in tanker attacks, a verified nuclear deal that removes sanctions risk, or new pipeline supply that bypasses the strait entirely.
Everyone Around Switzerland Is Raising Rates. It Just Sat Still

The Swiss National Bank left its policy rate at 0% on Thursday, 24 September 2026. The Swiss National
Bank decision
stands out because its neighbours went the other way. In its own statement, the SNB noted
that key rates were raised both in the euro area and in the US. Switzerland can afford to wait, for now,
because its inflation remains low.

What the Swiss National Bank decision kept in place

The policy rate stays at 0%. Banks’ sight deposits at the SNB earn that rate up to a threshold. Above
it, the discount remains 0.25 percentage points. The bank also repeated that it is willing to act in the
foreign exchange market as necessary. Those details come from the
SNB’s monetary policy assessment.

The SNB called its stance "appropriate" to keep inflation within the range it defines as price
stability. That range is 0% to 2%.

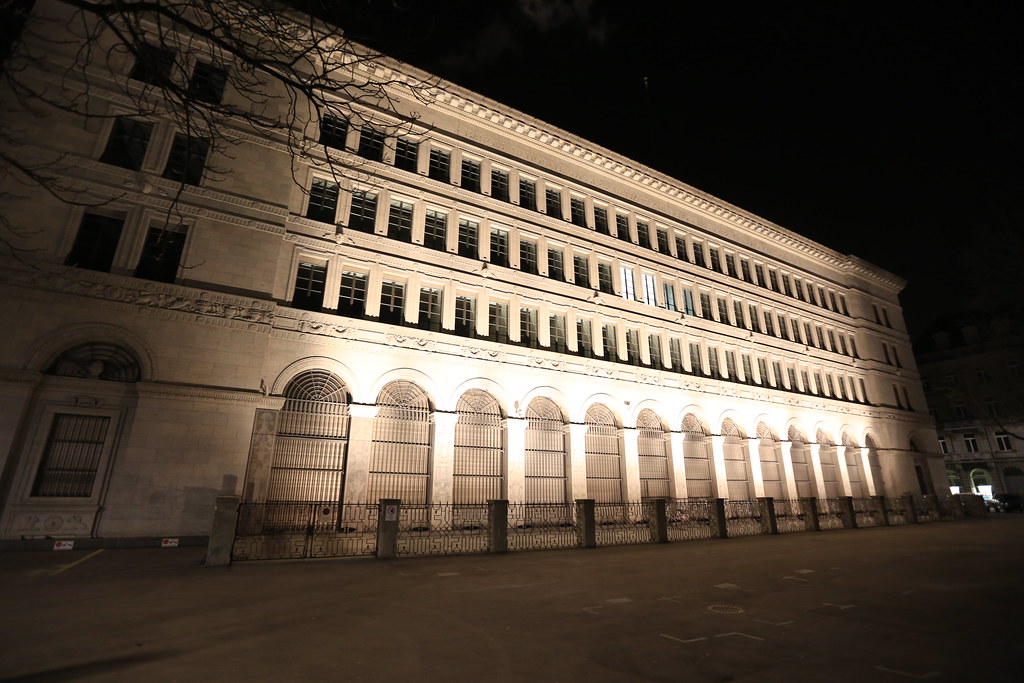
Swiss National Bank office in Zurich, one of the two seats behind the Swiss National Bank decision
The SNB runs head offices in Bern and Zurich.

The inflation picture behind the hold

Prices are rising, just slowly. Swiss inflation climbed from 0.6% in May to 0.8% in August. Goods
inflation turned positive in August for the first time since May 2024. Higher prices for oil products
drove most of that move.

The SNB expects inflation to rise a little further in the fourth quarter. It then sees it easing
during 2027 as energy inflation fades. Its conditional forecast reads:

  • 2026: 0.7% average inflation
  • 2027: 0.8%
  • 2028: 0.8%

That path stays inside the target band throughout. It assumes the policy rate holds at 0% over the
whole horizon. The bank said the medium-term forecast edged up partly because the Swiss franc has
weakened.

Why the Swiss National Bank decision diverges from the Fed and ECB

The contrast with other big central banks is the story. The US Federal Reserve raised its target range
to 3.75%-4.00% in September, its first hike since 2023, as CNBC reported.
Our coverage of the Fed’s rate hike explains
what drove that vote. The European Central Bank also tightened, as set out in our report on the
ECB interest rate hike.

Both face inflation above their 2% goals, much of it tied to energy. Switzerland does not. Its inflation
sits well below 1%. That gives the SNB room to hold while others squeeze.

A weaker franc helps the Swiss economy in the short run. The SNB said the recent depreciation is
having a supportive effect on growth.

The global backdrop matters here. The SNB noted that key rates rose in both the euro area and the US,
while inflation in many countries stayed above target on higher energy prices. Its own base case sees
moderate global growth ahead. It also sees inflation staying elevated for some time. That external picture
shapes how long Switzerland can keep its own rate at zero.

What the SNB expects for the Swiss economy

Second-quarter GDP growth was exceptionally strong. The SNB said an unusual surge in chemicals and
pharmaceuticals overstated the underlying pace. Even without it, growth was solid and broad-based.

There are soft spots. Capacity use sat below average, especially in manufacturing. Unemployment rose
again somewhat through early summer. The bank now expects growth of 1.5% to 2% for 2026, and around 1.5%
for 2027.

Where Swiss rates go from here

The SNB flagged the Middle East as the biggest risk. If energy prices end up significantly higher,
inflation would rise and growth would slow. Trade policy and exchange rates remain further sources of
uncertainty.

For savers and borrowers in Switzerland, little changes today. Mortgage and deposit rates tied to the
policy rate should stay near current levels. For currency watchers, the key variable is the franc. A much
weaker franc would push imported inflation up and test the 0% setting. The SNB holds its assessments
quarterly, so the next scheduled decision falls in December.

Swiss rate questions, answered

What did the Swiss National Bank decide?

On 24 September 2026 the SNB left its policy rate unchanged at 0%. The discount on sight deposits above the exemption threshold also stayed at 0.25 percentage points.

Why did the SNB hold while other central banks raised rates?

Swiss inflation is still inside the SNB’s 0-2% target range. It stood at 0.8% in August. The US Federal Reserve and the European Central Bank face inflation above target, which pushed them to hike.

What is the SNB’s inflation forecast?

The conditional forecast puts average inflation at 0.7% for 2026, 0.8% for 2027 and 0.8% for 2028. It assumes the policy rate stays at 0% throughout.

Will the SNB intervene in currency markets?

The SNB said it remains willing to be active in the foreign exchange market as necessary. It did not say whether it has intervened recently.

How fast is the Swiss economy growing?

The SNB expects growth of 1.5% to 2% in 2026 and around 1.5% in 2027. It said strong second-quarter GDP partly reflected an unusual boost from chemicals and pharmaceuticals.

What is the main risk the SNB flagged?

The situation in the Middle East. The SNB warned that energy prices could turn out significantly higher than expected, which would raise inflation and curb growth.

Sources

  • Swiss National Bank — Monetary policy assessment of 24 September 2026. snb.ch
  • CNBC — Fed rate decision September 2026: Rates rise to 3.75%-4%. cnbc.com

Images: featured photo by Robbie Conceptuel (CC0); in-article photo by TravelingOtter, licensed CC BY.

Fed Rate Hike Lifts Benchmark to 3.75%-4% in Policy Turn

The Federal Reserve delivered a Fed rate hike on 16 September 2026, lifting the target range for the federal funds rate by a quarter of a percentage point to 3.75%-4.00%. The Federal Open Market Committee voted unanimously, 12-0. It is the first increase since 2023, and it reverses the direction policy had been travelling for most of the past two years.

The Committee framed the move as unfinished business rather than a new emergency. “Inflation remains elevated,” it said in its statement, adding that the action “will support a timelier return to the Committee’s 2 percent goal.”

The decision in numbers

The target range moves from 3.50%-3.75% to 3.75%-4.00%. The implementation note published by the Federal Reserve Board sets out the corresponding adjustments to the administered rates that keep the effective funds rate inside that band.

What separates this from a routine quarter-point step is the direction. Markets had spent two years pricing a path that trended down. A unanimous vote to go the other way removes the argument that the Committee is split on whether the inflation problem has been solved.

What Kevin Warsh said

In his opening statement at the post-meeting press conference, Chair Kevin Warsh said inflation had remained too high for too long, and that recent readings had not shown a meaningful improvement in the underlying trend. That is a deliberately narrow claim: not that inflation is accelerating, but that the disinflation many had assumed was continuing has not shown up in the data with enough consistency to act on.

It was Warsh’s second meeting as chair; his first was in June 2026. Reporting from CNBC’s coverage of the decision characterised the accompanying message as more hawkish than the hike itself.

The projections matter more than the hike

The quarter point was widely expected. The Committee’s updated projections were not fully priced. Sixteen of eighteen policymakers now anticipate at least one further quarter-point increase before the end of 2026. Only two see the rate staying where it is. Officials’ year-end projections sit between roughly 4.1% and 4.4%.

A single hike can be read as insurance. A hike plus a near-unanimous expectation of another is a forecast that the Committee thinks the level of rates, not just the direction, was wrong.

How this sits against other central banks

The Fed is not moving in isolation. The European Central Bank has already been navigating its own turn, covered in our report on the ECB’s interest rate decision this year. Where the two diverge is in the starting point and in how much slack each economy still has.

Rate-sensitive assets responded immediately, including the moves in metals set out in our note on gold’s slide to a six-week low. Bank research desks have been revising their year-end paths accordingly, as tracked in our summary of one major bank’s 2026 forecast.

What it means away from the trading floor

For households, the transmission is slow but not subtle. Variable-rate borrowing reprices first, followed by new fixed-rate lending as banks reset their offers. Savers see the benefit sooner than borrowers see the cost, because deposit rates can move within days while most existing loans reprice on a schedule.

For companies, the question is refinancing. Debt raised during the low-rate years matures on a calendar that does not care about the policy cycle, and each maturity now rolls into a materially higher coupon. Businesses with staggered maturities absorb that gradually; those with concentrated refinancing dates do not.

For governments outside the United States, a higher federal funds rate tightens conditions without any domestic decision being taken. Dollar borrowing costs rise, currencies managed against the dollar come under pressure, and central banks face a choice between defending the exchange rate and supporting domestic demand.

What follows from here

Three things are worth watching. The first is the next inflation print, because the Committee has now tied itself explicitly to the underlying trend rather than headline readings. The second is whether the two dissenting projections become a bloc; unanimity on a decision does not mean unanimity on the path. The third is the transmission lag. A rate that has moved once after two years of the opposite signal takes time to filter into credit conditions, and the Committee has said it will judge by what the data shows rather than by a pre-set schedule.

The Fed’s next scheduled opportunity to act falls before year-end. On its own projections, most of the Committee expects to use it.

Questions readers are asking

How much did the Federal Reserve raise rates in September 2026?

The Federal Open Market Committee raised the target range for the federal funds rate by 25 basis points, to 3.75%-4.00%, at its meeting on 16 September 2026. The vote was unanimous at 12-0.

When did the Fed last raise interest rates before this?

The last increase before September 2026 was in 2023. Every move in between was either a cut or a hold, which is why this decision is being described as a turn rather than a continuation.

Why did the Fed hike instead of holding?

The Committee said inflation remains elevated and that the action would support a timelier return to its 2% goal. Chair Kevin Warsh said recent readings had not shown meaningful improvement in the underlying trend.

Is another rate increase expected in 2026?

The Committee’s own projections show 16 of 18 policymakers expecting at least one more quarter-point increase before the end of 2026. Only two saw rates staying where they are.

Where do Fed officials think rates end the year?

Year-end 2026 projections from officials cluster between 4.1% and 4.4%, which implies at least one more quarter-point step from the new 3.75%-4.00% range.

Does a Fed hike affect borrowers outside the United States?

Indirectly, yes. The federal funds rate anchors dollar funding costs worldwide, so dollar-denominated debt, trade finance and currencies managed against the dollar all tend to move when the Fed shifts direction.

The Asia Oil Price Shock Lands on Economies With No Room

Brent crude has pushed back above $100 a barrel, and the Asia oil price shock is landing on economies that have almost no policy room left to absorb it. Japan, South Korea and India import the bulk of the crude that powers their industry. Indonesia and Thailand subsidise fuel, which converts a market price into a budget line.

Bloomberg framed it as a fresh test of the region’s resilience, arriving with inflation already running hot and both fiscal and monetary policy already tight.

Two different problems wearing the same clothes

Dearer oil hits Asian economies through two separate channels, and conflating them produces bad forecasts.

For import-dependent manufacturers — Japan, South Korea, and to a large extent India — the cost arrives as an input price. It widens the trade deficit, pressures the currency, and works through to consumer prices over one to two quarters. Central banks can respond, at the cost of growth.

For fuel subsidisers — Indonesia, Thailand and others — the cost arrives as a fiscal transfer. The government absorbs the gap between world price and pump price, so consumer inflation stays contained while the deficit widens. The pressure shows up in bond markets rather than CPI, and the political cost of removing a subsidy mid-shock is prohibitive.

Both are painful. They call for opposite responses, which is why a regional generalisation about “Asia” tends to mislead.

Why the market reaction has been calmer than the number suggests

Triple-digit oil used to reliably trigger growth scares. This time the reaction has been comparatively muted.

The reason offered by analysts is that investors read the move as a supply constraint driven by conflict rather than a demand-side energy crisis — a bounded, geopolitical premium rather than a structural repricing. Discussion of that reading appeared in market commentary following the move.

That reading holds only as long as the supply disruption stays bounded. It is worth noting the assumption explicitly, because it is doing a lot of work.

It is already in the data

This is no longer a forecast. US wholesale prices rose 0.4% in August, driven by energy — the release we covered in detail here. Elevated crude and refined product prices feed consumer indices with a lag, and Asian economies with higher energy weightings in their baskets will see it sooner than the US does.

The awkward part is the sequencing. The European Central Bank has already moved, raising rates in September, and the Federal Reserve meets on 16 September with markets leaning toward a hike, as set out in our preview. Asian central banks that follow face tightening into an oil-driven slowdown. Those that do not face currency pressure that makes imported energy still more expensive in local terms.

The subsidy arithmetic

For governments capping pump prices, the cost scales directly with both the crude price and consumption volume, and neither falls quickly.

Three imperfect options exist. Absorb the cost and widen the deficit. Pass some through and accept the inflation and the politics. Or narrow eligibility so support reaches lower-income households only — cleanest in theory, slow to implement, and dependent on transfer systems not every country has.

Most governments will default to absorbing it in the short run, which means the fiscal damage accumulates quietly and shows up later in borrowing costs.

India sits awkwardly between the two categories. It imports the large majority of its crude, which gives it the input-cost problem, and it retains politically sensitive fuel pricing, which gives it a version of the fiscal one. Japan and South Korea, by contrast, pass energy costs through more directly, so the pain appears faster in their inflation prints and more visibly in industrial margins.

Indicators worth tracking

  • Currency moves against the dollar. A weakening currency multiplies the local-currency cost of crude and is the fastest transmission channel.
  • Fuel subsidy announcements. Any adjustment to capped prices signals that a government has decided it can no longer absorb the gap.
  • Central bank commentary on “second-round effects”. That phrase is the tell that a bank has stopped treating the shock as temporary.

Questions on the oil shock

How high has oil actually gone?

Brent traded above $107 a barrel, having crossed $100 for the first time in months. Prices closed the week more than 8% higher.

Which Asian economies are most exposed?

Japan, South Korea and India through import dependence for industry; Indonesia and Thailand through the fiscal cost of fuel subsidies. The exposure differs in kind, not just degree.

Why has the market reaction been relatively muted?

Analysts attribute it to investors reading the rise as a conflict-driven supply constraint rather than a broad energy crisis. That interpretation depends on the disruption remaining contained.

Will this force Asian central banks to raise rates?

Not automatically. Standard practice is to look through supply-driven price rises, but that is harder when inflation is already above target. Watch for language about second-round effects.

How does a fuel subsidy change the picture?

It moves the cost from consumers to the government budget. Consumer inflation stays lower, the fiscal deficit widens, and the strain appears in bond markets instead of price indices.

How quickly does crude reach consumer prices?

Typically one to two quarters for the full pass-through, though fuel and transport costs move faster. Economies with higher energy weightings in their consumer baskets see it sooner.

We are tracking the central bank response across regions — see our coverage of the ECB’s September move.

Canada’s Central Bank Held Rates Steady — but Its Warning Is the Real Story

The Bank of Canada rate hold came on September 2, 2026. The central bank kept its target for the overnight rate unchanged at 2.25%, with the Bank Rate at 2.5% and the deposit rate at 2.20%. The decision matched what most economists had expected, according to the bank’s own official press release.

The tone of Governor Tiff Macklem’s remarks drew more attention than the hold itself. He said inflation risk is rising. He pointed to higher energy costs and new dollar-for-dollar tariffs on U.S. goods as the two biggest potential drivers of price increases ahead. CBC News flagged that warning as more hawkish in tone than the decision itself suggested.

Why the Bank of Canada Rate Hold Came With a Warning Attached

Macklem’s opening statement described recent economic data as suggesting growth has “regained some momentum” — ordinarily a reason for confidence. He paired that with a caution: renewed trade tensions and geopolitical uncertainty could shift the inflation outlook quickly. That left the bank unwilling to commit to a clear path for its next move.

The tariff dynamic sits at the center of that caution. Canada has been rolling out retaliatory tariffs on U.S. goods amid an ongoing trade dispute, a policy Tamara News covered in our report on Canada’s retaliatory tariffs. Tariffs typically raise costs for businesses and consumers — exactly the inflationary pressure Macklem flagged.

Energy costs add a second layer to that risk. Canada’s economy is more exposed to swings in oil and gas prices than many peer economies, both as a major producer and as a country where heating and transport costs move household budgets noticeably. A tariff-driven cost increase arriving alongside higher energy prices would compound rather than offset each other. That is likely why Macklem flagged both risks together instead of treating them separately.

How This Bank of Canada Rate Hold Compares to Other Central Banks

Canada’s hold sits alongside a broader split among major central banks this month. The Bank of England is leaning toward no change at its own September meeting. The U.S. Federal Reserve faces a closer call — Tamara News detailed the Fed’s mixed signals in our coverage of the Federal Reserve’s rate outlook. Some other central banks are leaning toward raising rates rather than holding, which shows how differently inflation pressure is playing out across economies this year.

What a Held Rate Means for Canadians

A hold keeps borrowing costs — mortgages, lines of credit, business loans — unchanged rather than cheaper or more expensive. For households renewing mortgages this year, stability generally beats a surprise increase. But Macklem’s warning suggests the bank is leaving room to raise rates later if tariff-driven inflation materializes, rather than promising continued stability indefinitely.

Businesses planning capital spending face a similar calculus. A steady rate makes financing costs predictable in the near term. Macklem’s language leaves little doubt that predictability could end at the next meeting if incoming data shows tariffs and energy costs feeding through into broader prices faster than expected.

What the Bank of Canada Watches Next

The bank’s next scheduled interest rate announcement is October 28, 2026. Between now and then, watch how quickly the retaliatory tariffs with the U.S. actually feed through into consumer prices. Watch too whether energy costs keep climbing. Either trend accelerating would raise the odds of a rate increase at the October meeting rather than another hold. Financial markets will parse every public comment from Macklem and other officials for hints of which way that decision is leaning. Central bank communication between meetings often moves borrowing costs and currency markets almost as much as the meetings themselves.

The Canadian dollar’s performance against the U.S. dollar will be one signal worth watching too. A currency that weakens sharply on tariff news would add yet another inflation channel. A cheaper loonie makes imported goods more expensive for Canadian consumers, regardless of what the Bank of Canada does with its policy rate.

Provincial governments with energy-heavy economies, including Alberta, face a different calculus than provinces more exposed to manufacturing trade with the U.S. A rate decision built around a national average inevitably lands unevenly across regions with very different economic profiles. That is part of why the bank’s public commentary tends to stay carefully general rather than naming specific sectors or provinces by name.

Fixed-rate mortgages have generally stayed more popular than variable-rate products with Canadian borrowers in recent years. That preference tends to strengthen whenever a central bank signals it may not hold steady indefinitely, since locking in a known rate removes the risk of a future increase entirely.

Canadian currency notes after the Bank of Canada rate hold

FAQs on the Bank of Canada Rate Hold

What is Canada’s overnight interest rate after this decision?
2.25%, unchanged from the previous setting, with the Bank Rate at 2.5% and the deposit rate at 2.20%.

Why did the Bank of Canada hold rates instead of cutting or raising them?
Governor Tiff Macklem said growth has regained some momentum, but flagged rising inflation risk from tariffs and energy costs that make the future path uncertain.

What tariffs is Macklem referring to?
New dollar-for-dollar retaliatory tariffs between Canada and the United States, part of an ongoing trade dispute between the two countries.

When is the Bank of Canada’s next rate decision?
October 28, 2026.

How does this compare to what other central banks are doing?
The Bank of England is also leaning toward holding, while the U.S. Federal Reserve’s September decision remains a closer call between a hold and a hike.

Featured image: “Centre Block, Ottawa, Southeast view 20170422 1.jpg” by DXR (CC BY-SA 4.0), via Wikimedia Commons.