Anthropic Is Quietly Planning the Biggest IPO in History — Here’s the Number Investors Are Chasing

Anthropic is reportedly working toward a stock listing that could value the AI company at up to $2 trillion, which would make it the largest initial public offering in history by a wide margin. According to a Bloomberg report relayed by Yahoo Finance on 2 October 2026, prospective investors see a fair-value range of $1.8 trillion to $2 trillion. The Anthropic IPO valuation target has shifted since earlier reporting, and the company itself has not confirmed either the number or the date.

The Anthropic IPO valuation target, from October to a pre-Thanksgiving debut

Investors had previously expected Anthropic to list in October 2026 at a valuation of $2 trillion or more. That timeline has since moved: the company is now reportedly aiming for a listing before the Thanksgiving holiday on 26 November, with bankers potentially starting the roadshow the week of 9 November. Anthropic is said to be hosting investors at its San Francisco headquarters in the run-up to that window. The company is still said to be targeting a debut by year-end at the latest, even if the exact week keeps moving.

Morgan Stanley, Goldman Sachs and JPMorgan Chase are reportedly leading the offering. Anthropic is also said to be considering super-voting shares that would hand CEO Dario Amodei and his fellow co-founders outsized control after the company goes public, a structure increasingly common among founder-led tech listings.

The numbers behind the number

Anthropic’s valuation path has moved fast. A Series A round in May 2021 valued the company at roughly $623 million, according to research published by GraniteShares, an ETF issuer with its own commercial interest in AI-linked products. By May 2026, a $65 billion Series H round put the company’s post-money valuation at $965 billion. Anthropic confidentially submitted a draft S-1 registration to the SEC on 1 June 2026.

On the revenue side, Anthropic reportedly posted about $4.6 billion in 2025 revenue, up from $386 million the year before, with the growth accelerating sharply through 2026: GraniteShares cites an annualised run rate climbing from roughly $14 billion in February to around $30 billion by April, and reportedly past $65 billion by the end of July. Second-quarter 2026 revenue came in above $11.5 billion, against $787 million a year earlier, and the company reportedly reached positive adjusted operating income in that quarter. A $2 trillion valuation would work out to roughly 31 times that run rate and about 10 times an internally projected 2028 revenue figure of $190 billion to $200 billion.

Why the net loss looks so much bigger than it sounds

Anthropic’s 2025 net loss has been reported at nearly $42 billion, a figure that sounds alarming next to $4.6 billion in revenue. More than $34 billion of that loss, however, came from accounting adjustments tied to the fair value of liabilities rather than cash actually leaving the business. The company’s separate operating loss for 2025, the more standard measure of whether the underlying business is burning cash, was reported at a bit over $8 billion, a large number but a very different one from $42 billion.

What to watch before any S-1 goes public

Everything here still rests on unnamed sources and a process both Bloomberg and GraniteShares describe as fluid. Amazon holds roughly 21% of Anthropic and Alphabet about 15%, meaning both companies have a direct financial stake in how this listing turns out. The reporting also notes that rival OpenAI has reportedly postponed its own IPO, and that both companies face scrutiny over AI-related security concerns. The real test comes once Anthropic’s S-1 becomes public and investors get an actual prospectus to pick apart, rather than a run rate relayed secondhand through anonymous sources.

Frequently asked questions

What valuation is Anthropic reportedly targeting for its IPO?
Bloomberg sources cited by Yahoo Finance put prospective investors’ fair-value range at $1.8 trillion to $2 trillion. If reached, that would be the largest IPO valuation in history, though Anthropic has not officially confirmed a number.

When is the Anthropic IPO valuation target expected to go public?
Reports now point to a listing before the Thanksgiving holiday on 26 November 2026, with a possible roadshow starting the week of 9 November. Anthropic had earlier been expected to list in October, and the company still says it aims to debut by year-end at the latest.

Which banks are leading Anthropic’s IPO?
Morgan Stanley, Goldman Sachs and JPMorgan Chase are reportedly leading the offering, according to Bloomberg sources relayed by Yahoo Finance.

How big is Anthropic’s business right now?
The company reportedly posted about $4.6 billion in 2025 revenue, up from $386 million in 2024, and reached positive adjusted operating income in the second quarter of 2026, even as its overall 2025 net loss topped $40 billion on paper.

Why did Anthropic report such a large net loss if business is growing?
More than $34 billion of the reported 2025 net loss came from accounting adjustments tied to the fair value of liabilities, not from actual cash leaving the business. The company’s 2025 operating loss, a separate and smaller figure, was reported at over $8 billion.

Is the $2 trillion figure confirmed?
No. Both the valuation and the timeline come from unnamed sources cited by Bloomberg, and the reporting itself notes that the process remains fluid and that dates are subject to change.

For related coverage, see our earlier look at Anthropic’s third-quarter revenue and cash flow turn and OpenAI’s own recent policy reversal.
Historic stock exchange floor illustrating the scale of the Anthropic IPO valuation target

OPEC+ Could Have Pumped More Oil This Month — Here’s Why It Didn’t

Seven OPEC+ countries agreed on 4 October 2026 to leave their November 2026 crude production targets unchanged, according to a group press release reported by Enerdata. The OPEC+ November output decision is the second straight month the group has held steady rather than following through on the output increases it had signalled earlier in 2026.

Who agreed to what

The decision came out of a virtual meeting among Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman. Their individual targets for November are set at 10.5 million barrels per day for Saudi Arabia, 9.9 million for Russia, 4.4 million for Iraq, 2.7 million for Kuwait, 1.6 million for Kazakhstan, 1 million for Algeria and 0.8 million for Oman. Those numbers match what the group had already set for October, meaning no formal increase takes effect for the second consecutive round.

Why the OPEC+ November output decision stayed flat

For much of 2026, OPEC+ had been unwinding years of production cuts, gradually raising targets as it tried to claw back market share. That plan has run into a problem the group’s own quotas can’t fix: actual exports are falling short of targets regardless of what gets agreed on paper. According to Enerdata’s account, the ongoing Middle East conflict has disrupted exports through the Strait of Hormuz, a chokepoint that a large share of Gulf oil has to pass through, while separate limits on Russian oil flows are constraining Moscow’s output independently of anything OPEC+ decides. Enerdata’s own reporting does not include the group’s official stated rationale, so this explanation reflects the analyst’s reading of the situation rather than an on-record OPEC+ statement.

A separate OPEC press release confirms the seven countries’ agreement to hold steady. In effect, the group is holding targets flat partly because raising them further would do little right now. If tankers can’t move through Hormuz at full volume and Russian flows are already constrained, announcing a higher headline target doesn’t translate into more oil actually reaching buyers.

What this means for prices and buyers

A flat output decision removes one obvious source of extra supply hitting the market in November, but it does not automatically push prices in one direction. Oil prices are shaped by a mix of factors: how much OPEC+ members are really exporting against their targets, how demand is tracking heading into the northern hemisphere winter, and how the regional conflict affects shipping and insurance costs for tankers moving through contested waters. Buyers in energy-importing countries should expect continued volatility tied to Hormuz-related headlines rather than a clean, predictable price path.

Where oil output goes from here

OPEC+ reviews its production targets on a recurring monthly cycle, so the next decision will set targets for December 2026. That meeting will be a clearer test of direction: if Hormuz disruptions ease and Russian export limits loosen, the group may finally move on the increases it has twice now deferred. If the disruptions persist or worsen, expect a third straight month of targets staying put, or even talk of fresh cuts if oversupply fears give way to concerns about actual availability.

Frequently asked questions

What did OPEC+ decide for November 2026?
Seven OPEC+ countries, Saudi Arabia, Russia, Iraq, Kuwait, Kazakhstan, Algeria and Oman, agreed at a virtual meeting on 4 October 2026 to keep their required crude production targets for November 2026 unchanged from October.

Why didn’t OPEC+ raise output as planned?
OPEC+ had been raising output targets through much of 2026 after years of cuts, but the Middle East conflict has disrupted exports through the Strait of Hormuz and limited Russian oil flows, keeping actual group output below the targets it set.

What are the individual OPEC+ November output decision targets?
Saudi Arabia 10.5 million barrels per day, Russia 9.9 million, Iraq 4.4 million, Kuwait 2.7 million, Kazakhstan 1.6 million, Algeria 1 million and Oman 0.8 million, according to Enerdata’s reporting of the group’s own figures.

Does this mean oil prices will rise?
Not necessarily on its own. Keeping targets flat removes one source of extra supply, but prices also depend on demand, how much member countries are actually exporting versus their targets, and how the Middle East conflict affects shipping routes.

Is this the first time OPEC+ has paused its planned increases?
No. The group had also kept its September 2026 targets unchanged in the prior round, meaning November marks a second consecutive month without the increases OPEC+ had signalled earlier in the year.

When does OPEC+ meet again?
OPEC+ holds its production decisions on a recurring monthly cycle, with the next review expected to set targets for December 2026 based on how exports and the regional conflict are tracking by then.

For more on where energy and commodity markets stand this week, see our coverage of the EIA’s 2027 oil supply forecast and gold’s recent move against a stronger dollar.

Oil production equipment tied to the OPEC+ November output decision

Rubio’s Blunt Warning to Venezuela: Reform Fast, Or Watch This Collapse

Venezuela’s political transition is entering a tense new phase. On 26 October 2026, US Secretary of State Marco Rubio told reporters that the alternative to a successful handover is either armed conflict or a return to the repression that marked the final years of Nicolás Maduro’s rule. “If this process doesn’t work, then the alternative is going to be worse,” he said, according to an IANS report carried by The Hans India.

Maduro himself is already out of power and in US custody, facing a fresh set of charges on top of earlier ones. In his place, interim president Delcy Rodríguez has been overseeing a government Washington still does not fully trust. Rubio’s remarks, delivered a day later on 27 October, make clear the transition’s deadline pressure has not eased just because Maduro is gone.

What Rubio said about Venezuela’s political transition

Speaking from Washington, Rubio set out a blunt framework for Venezuela’s political transition. According to a report from Agenzia Nova, he said the United States is prepared to use sanctions to push interim authorities to keep the commitments they have already made. He credited the interim government with meeting every deadline agreed so far, but warned that patience is not unlimited.

He was equally direct about accountability. Interim officials, Rodríguez included, “will be judged on their actions rather than their statements,” Rubio said, adding that immunity from prosecution is off the table for anyone in the interim government. That is a notably harder line than the kind of blanket amnesty often floated in negotiated transitions elsewhere.

Why the electoral council is the real sticking point

At the centre of Rubio’s demands sits an institutional problem rather than a political one. He wants Venezuela’s National Electoral Council and its Supreme Court replaced before any vote can be considered credible, arguing both bodies remain loaded with officials loyal to the old Maduro apparatus. “How can you have a legitimate election in Venezuela when the Electoral Council is controlled by people loyal to one side,” he said.

No fixed election date has been set. Rubio said Washington would not let interim leadership delay a vote indefinitely, but he also avoided naming a specific deadline, which leaves plenty of room for the kind of slow-walking that has derailed past transitions in the region.

Machado’s return and the sanctions lever

One concrete sign of progress: opposition leader María Corina Machado returned to Venezuela on 26 October without incident, Rubio said, after the US told interim authorities weeks earlier that her return should be permitted. Machado has publicly criticised a US-backed oil arrangement with a private company, but Rubio said those objections should not be allowed to derail the broader transition.

That oil arrangement is itself part of the leverage equation. Some sanctioned activity is currently allowed to continue under Treasury waivers and general licenses, which keep limited oil revenue flowing. Rubio suggested those waivers are conditional rather than permanent, and could be pulled back if the interim government falls behind on its commitments. He also said Washington’s broader goal includes making it possible for the estimated 6 to 7 million Venezuelans who left the country during the Maduro years to come home.

What happens from here

For now, Venezuela’s political transition remains a negotiation conducted mostly in public statements rather than signed documents. Rubio expressed confidence the process could be completed before his own time in office ends, which is as close as he came to putting a timeline on it. He also said Iranian and Cuban influence inside Venezuela has been sharply reduced since the transition began, a claim that, like much of this story, rests on the US government’s own account rather than independent verification.

The coming weeks are likely to turn on two concrete signals: whether the electoral council and court actually get replaced, and whether the oil waivers survive. Either one slipping would tell us more about where this transition is really headed than another round of statements.

Frequently asked questions

Why is Marco Rubio warning about civil war in Venezuela?
Rubio said that if the US-backed transition in Caracas stalls, the alternative is either armed conflict or a return to the repression of the Maduro era. He made the comments to reporters on 26 October 2026, framing the warning as pressure on interim authorities to move faster on reform.

Who is running Venezuela’s interim government?
Delcy Rodríguez has been acting as interim president since the transition began. Rubio said she and other interim officials would be judged on actions rather than statements, and ruled out immunity from prosecution for interim officials.

What does the US want changed before elections happen?
Washington wants Venezuela’s National Electoral Council (CNE) and Supreme Court (TSJ) replaced, arguing both are stacked with officials loyal to the former Maduro government and cannot run a credible vote.

Is María Corina Machado back in Venezuela?
Rubio said opposition leader María Corina Machado returned to Venezuela on 26 October 2026 without incident, after Washington told interim authorities weeks earlier that she should be allowed back.

Will the US lift sanctions on Venezuela?
Not unconditionally. Rubio said some oil-related activity is already permitted through Treasury waivers and general licenses, but warned those could be reconsidered if interim authorities fall behind on agreed commitments.

What happens if the transition fails?
Rubio framed it as a binary choice: reform that leads to a stable, internationally recognised government, or a slide back into armed conflict or authoritarian rule. He gave no fixed election date but said Washington would not let the process drag on indefinitely.

For more on how the region’s politics are moving this week, see our coverage of the charges Maduro now faces in US custody and the protests that preceded this transition.

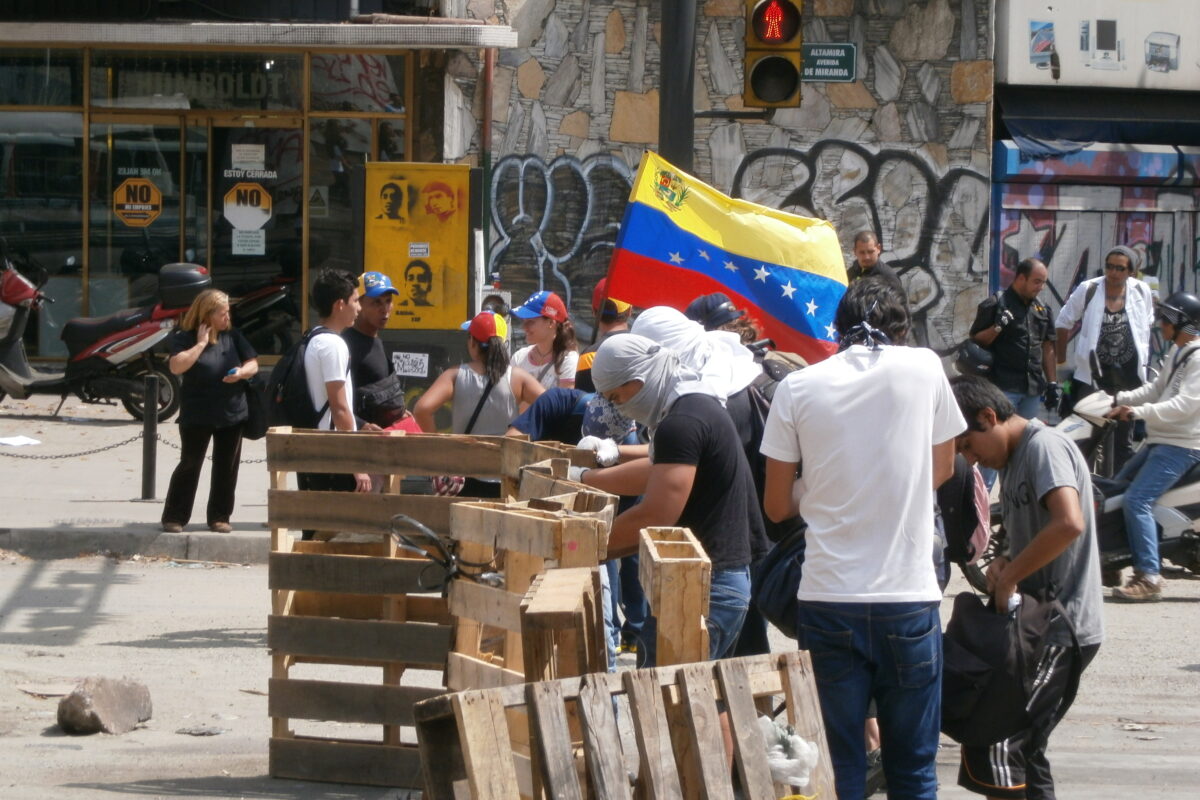
Crowd demonstrating as part of Venezuela's political transition away from the Maduro government

Israel Just Voted — And the Real Fight for Power Hasn’t Even Started

Israelis cast their ballots on 27 October 2026 in the first national election since the Hamas-led attack of 7 October 2023 and the war that followed. All 120 Knesset seats were up for grabs, and the vote has been widely framed as a referendum on Prime Minister Benjamin Netanyahu’s long run in office. But as with every Israeli election, the count itself only sets up the real contest: Israel election coalition math, which decides who actually governs.

A race too close to call on its own

Pre-election polling, summarised by Al Jazeera, put the opposition bloc at around 52 projected seats against roughly 50 for Netanyahu’s religious-nationalist alliance of Likud, Jewish Power and Religious Zionism. Neither side was projected to reach the 61 seats needed for a majority. That gap is the whole story here: defeating Netanyahu at the ballot box, if that is even what happened, does not automatically remove him from power.

The opposition side is not a single party but a loose alliance. Yashar, the Democrats, Yisrael Beytenu and the Together alliance signed a non-aggression pact in September 2026 specifically to avoid splitting the anti-Netanyahu vote. Yashar’s Gadi Eisenkot is seen as the group’s likeliest candidate for prime minister, with Naftali Bennett of Together also mentioned as an alternative.

Why Israel election coalition math runs through two small parties

As reference tracking of the race shows, the Joint List and Ra’am, which together represent Palestinian citizens of Israel, are projected to win about 13 seats. In a Knesset where neither major bloc clears 61 on its own, that bloc of seats could end up deciding who forms the next government, whether by joining a coalition directly or by backing one from outside without taking cabinet posts. Most opposition leaders have so far rejected governing with Ra’am inside the coalition, which narrows an already tight path.

This is where Israel’s electoral system does its real work. Under proportional representation, no single party has ever won an outright Knesset majority, so every government since the state’s founding has been a negotiated coalition. The prime minister is not chosen directly by voters on election day; Knesset members effectively choose afterward, through weeks of bargaining over ministries, policy commitments and, often, personal rivalries.

The paths that are actually on the table

Several outcomes remain plausible once the final results are certified. A Netanyahu-led government is still possible if his bloc can find even a handful of additional seats through defections or late deals. An opposition-led majority is possible if Eisenkot or Bennett’s camp can stitch together support without relying on Ra’am’s votes inside the coalition. A minority government, propped up from outside by Arab-led parties that don’t take ministries, is a third route that has precedent in Israeli politics. A national unity government, or a rotating premiership arrangement between rival blocs, remains a longer-shot fourth option.

If none of that works, Israel would likely head to yet another election, a familiar pattern in a country that went to the polls five times between 2019 and 2022 alone. Netanyahu would stay on as caretaker prime minister in the meantime, which is itself a form of leverage in the negotiations to come.

What to watch next

The real signal in the days ahead will not be the headline seat count but which smaller parties start talking to which larger ones. Watch whether Shas and United Torah Judaism, the ultra-Orthodox parties that have both joined and abandoned Netanyahu’s coalitions before, swing toward him or stay on the sidelines. Watch whether Ra’am is offered any formal role or kept firmly outside the room. And watch how long the process takes: Israeli coalition talks have dragged on for months before, and a drawn-out negotiation is itself a kind of outcome, leaving Netanyahu in charge by default while his rivals try to agree on who should replace him.

Frequently asked questions

When is Israel’s 2026 election and why does it matter?
Israelis voted on 27 October 2026 for all 120 Knesset seats, the first election since the Hamas-led attack of 7 October 2023 and the war that followed. It is widely seen as a referendum on Benjamin Netanyahu’s long tenure as prime minister.

Did Netanyahu lose the election?
Pre-election polling put the opposition bloc at roughly 52 projected seats against about 50 for Netanyahu’s religious-nationalist alliance, with neither side projected to reach the 61 needed for a majority. The actual count determines nothing on its own; coalition talks do.

Who leads the opposition to Netanyahu?
Four parties, Yashar, the Democrats, Yisrael Beytenu and the Together alliance, signed a non-aggression pact in September 2026 to try to unseat Netanyahu. Yashar’s Gadi Eisenkot is seen as the likeliest prime ministerial candidate, with Naftali Bennett of Together also mentioned.

Why do Arab-led parties matter so much in this election?
The Joint List and Ra’am, which represent Palestinian citizens of Israel, are projected to win around 13 seats combined. With neither major bloc projected to reach 61 seats alone, those seats could decide who ends up forming a government.

How is Israel’s prime minister actually chosen?
Not directly by voters. Israel uses proportional representation, so Knesset members negotiate alliances after the vote until one side can command 61 seats. No party has ever won an outright majority on its own.

What happens if no coalition can be formed?
Israel would likely face another election, and Netanyahu would remain as caretaker prime minister until a new government is sworn in. That scenario has played out more than once in Israeli politics over the past decade.

For related coverage, see our reports on the proposed window for Russia-Ukraine peace talks and Venezuela’s own contested transition.

The Knesset building, the venue for Israel election coalition math negotiations after the 2026 vote