Monthly Archives: September 2026

Positron AI Funding Round Bets $875M Against the HBM Shortage

Positron AI has closed an $875 million Series C at a $5 billion post-money valuation, and the Positron AI funding round is a bet on a specific contrarian idea: that the memory bottleneck in AI inference can be solved with cheap commodity chips instead of the scarce, expensive high-bandwidth memory everyone else is fighting over.

The company announced the raise in two tranches: $375 million in the Series C proper, and a Series C-1 of up to $500 million.

The bet: skip HBM entirely

Inference workloads are memory-hungry. Serving a large model means holding enormous weights close enough to the compute to be read fast, which is why high-bandwidth memory has become the industry’s tightest constraint — supply is limited, advanced packaging capacity is limited, and Nvidia absorbs much of both.

Positron’s next-generation chip, Asimov, pairs its compute architecture with 288GB to 2,304GB of LPDDR5X per chip. LPDDR5X is commodity memory, the kind that goes into phones and laptops. It is slower per bit than HBM and vastly more available.

The wager is that for inference specifically, capacity beats peak bandwidth — that fitting more of the model in memory matters more than reading any single part of it at maximum speed. If that holds, Positron sidesteps the supply chain that constrains its competitors.

It is an engineering claim, not yet a proven one, and the company is the party asserting it.

Who wrote the cheques

The round was co-led by NEA, Atreides Management, Valor Equity Partners, Andra Capital, Dylan Patel’s SemiAnalysis Capital, and Jim Clark — the founder of Silicon Graphics and Netscape.

Additional investors include the Qatar Investment Authority, DFJ Growth, Cisco Investments, Hudson River Trading and Naver Ventures, alongside existing backers.

Two names stand out for what they signal. SemiAnalysis Capital is the investment arm attached to a research operation that scrutinises exactly this kind of architectural claim, which makes its participation a form of technical endorsement. Hudson River Trading is a high-frequency trading firm — a buyer whose entire business depends on inference latency, not a generalist fund.

Where the money goes

Per the company, the financing funds three things: the Asimov tapeout; a 2MW-plus engineering data centre and emulation platform; and the production ramp of Titan, its current-generation inference system, including LPDDR5X supply commitments and go-to-market expansion.

Asimov is scheduled to tape out on TSMC’s N3P process at the end of 2026, with production targeted for the second half of 2027, as SiliconANGLE reported.

That timeline is the thing to hold onto. Silicon announced in 2026 for production in late 2027 has roughly eighteen months of execution risk ahead of it, in a market where the competitive baseline moves every quarter.

Titan is what bridges the gap. It is the current-generation system, shipping now, and the LPDDR5X supply commitments funded by this round are as much about securing memory allocation for that ramp as about the future chip. Commodity memory is abundant relative to HBM, but “abundant” is not the same as “available at volume on contract”, and locking supply early is how a company avoids becoming the constraint it was designed to escape.

The competitive picture it enters

Inference silicon has become the most contested corner of the AI hardware market, because it is where the recurring revenue is — training happens in bursts, inference runs continuously.

The incumbents are not standing still. Qualcomm committed to a large-scale inference partnership with Amazon, covered in our report on that deal, and Nvidia’s manoeuvring in the space has drawn antitrust attention, as we set out in the DOJ’s look at the Groq arrangement.

A $5 billion valuation for a company whose flagship product ships in eighteen months prices in a lot of confidence. The structure of the raise — a second tranche of “up to” $500 million — suggests the investors built themselves some optionality about how much of that confidence to fund immediately.

The question that decides it

Whether commodity memory is genuinely good enough for production inference at scale, or good enough only for workloads where latency tolerance is generous.

Positron says the former. Its customers will establish which is true, and the evidence arrives in 2027. Until then, the round is a well-capitalised hypothesis.

Questions about the raise

How much did Positron raise and at what valuation?

$875 million total at a $5 billion post-money valuation, split into a $375 million Series C and a Series C-1 of up to $500 million.

What is different about the Asimov chip?

It uses commodity LPDDR5X memory — 288GB to 2,304GB per chip — rather than high-bandwidth memory, avoiding the HBM and advanced packaging supply constraints that limit competing inference hardware.

When will Asimov be available?

It is scheduled to tape out on TSMC’s N3P process at the end of 2026, with production targeted for the second half of 2027.

Who led the round?

Co-leads were NEA, Atreides Management, Valor Equity Partners, Andra Capital, SemiAnalysis Capital and Jim Clark. Other investors include the Qatar Investment Authority, Cisco Investments and Hudson River Trading.

Is Positron competing directly with Nvidia?

In inference, yes. It is not targeting training workloads, where Nvidia’s position is strongest.

What is the main risk?

Execution and timing. The flagship chip is roughly eighteen months from production in a market where competing hardware advances continuously, and the performance claim for commodity memory is not yet demonstrated at scale.

More on the inference hardware race in our coverage of the Qualcomm-Amazon agreement and Google’s European data centre build-out.
The Asia Oil Price Shock Lands on Economies With No Room

Brent crude has pushed back above $100 a barrel, and the Asia oil price shock is landing on economies that have almost no policy room left to absorb it. Japan, South Korea and India import the bulk of the crude that powers their industry. Indonesia and Thailand subsidise fuel, which converts a market price into a budget line.

Bloomberg framed it as a fresh test of the region’s resilience, arriving with inflation already running hot and both fiscal and monetary policy already tight.

Two different problems wearing the same clothes

Dearer oil hits Asian economies through two separate channels, and conflating them produces bad forecasts.

For import-dependent manufacturers — Japan, South Korea, and to a large extent India — the cost arrives as an input price. It widens the trade deficit, pressures the currency, and works through to consumer prices over one to two quarters. Central banks can respond, at the cost of growth.

For fuel subsidisers — Indonesia, Thailand and others — the cost arrives as a fiscal transfer. The government absorbs the gap between world price and pump price, so consumer inflation stays contained while the deficit widens. The pressure shows up in bond markets rather than CPI, and the political cost of removing a subsidy mid-shock is prohibitive.

Both are painful. They call for opposite responses, which is why a regional generalisation about “Asia” tends to mislead.

Why the market reaction has been calmer than the number suggests

Triple-digit oil used to reliably trigger growth scares. This time the reaction has been comparatively muted.

The reason offered by analysts is that investors read the move as a supply constraint driven by conflict rather than a demand-side energy crisis — a bounded, geopolitical premium rather than a structural repricing. Discussion of that reading appeared in market commentary following the move.

That reading holds only as long as the supply disruption stays bounded. It is worth noting the assumption explicitly, because it is doing a lot of work.

It is already in the data

This is no longer a forecast. US wholesale prices rose 0.4% in August, driven by energy — the release we covered in detail here. Elevated crude and refined product prices feed consumer indices with a lag, and Asian economies with higher energy weightings in their baskets will see it sooner than the US does.

The awkward part is the sequencing. The European Central Bank has already moved, raising rates in September, and the Federal Reserve meets on 16 September with markets leaning toward a hike, as set out in our preview. Asian central banks that follow face tightening into an oil-driven slowdown. Those that do not face currency pressure that makes imported energy still more expensive in local terms.

The subsidy arithmetic

For governments capping pump prices, the cost scales directly with both the crude price and consumption volume, and neither falls quickly.

Three imperfect options exist. Absorb the cost and widen the deficit. Pass some through and accept the inflation and the politics. Or narrow eligibility so support reaches lower-income households only — cleanest in theory, slow to implement, and dependent on transfer systems not every country has.

Most governments will default to absorbing it in the short run, which means the fiscal damage accumulates quietly and shows up later in borrowing costs.

India sits awkwardly between the two categories. It imports the large majority of its crude, which gives it the input-cost problem, and it retains politically sensitive fuel pricing, which gives it a version of the fiscal one. Japan and South Korea, by contrast, pass energy costs through more directly, so the pain appears faster in their inflation prints and more visibly in industrial margins.

Indicators worth tracking

  • Currency moves against the dollar. A weakening currency multiplies the local-currency cost of crude and is the fastest transmission channel.
  • Fuel subsidy announcements. Any adjustment to capped prices signals that a government has decided it can no longer absorb the gap.
  • Central bank commentary on “second-round effects”. That phrase is the tell that a bank has stopped treating the shock as temporary.

Questions on the oil shock

How high has oil actually gone?

Brent traded above $107 a barrel, having crossed $100 for the first time in months. Prices closed the week more than 8% higher.

Which Asian economies are most exposed?

Japan, South Korea and India through import dependence for industry; Indonesia and Thailand through the fiscal cost of fuel subsidies. The exposure differs in kind, not just degree.

Why has the market reaction been relatively muted?

Analysts attribute it to investors reading the rise as a conflict-driven supply constraint rather than a broad energy crisis. That interpretation depends on the disruption remaining contained.

Will this force Asian central banks to raise rates?

Not automatically. Standard practice is to look through supply-driven price rises, but that is harder when inflation is already above target. Watch for language about second-round effects.

How does a fuel subsidy change the picture?

It moves the cost from consumers to the government budget. Consumer inflation stays lower, the fiscal deficit widens, and the strain appears in bond markets instead of price indices.

How quickly does crude reach consumer prices?

Typically one to two quarters for the full pass-through, though fuel and transport costs move faster. Economies with higher energy weightings in their consumer baskets see it sooner.

We are tracking the central bank response across regions — see our coverage of the ECB’s September move.

Yemen Displacement Crisis Quadruples in a Single Week

The Yemen displacement crisis has escalated sharply, with the United Nations reporting that at least 76,000 people have fled their homes since July — a figure that quadrupled in the space of a single week as Houthi forces pushed a large-scale offensive against government positions.

The International Organization for Migration described a situation deteriorating by the hour. UN News reported the surge on 12 September, with the sharpest concentration in the southwest.

Taiz is bearing most of it

Roughly 8,300 households — close to 50,000 people — have been displaced from districts in Taiz province alone. That is about two-thirds of the total from one governorate.

Taiz has been a front line for most of the war, but the current fighting is different in pace. The Houthis launched their offensive last week and have taken position after position, in fighting that Arab News reported has left hundreds dead. We covered the opening phase in our report on the week that killed 129; the toll and the displacement have both moved substantially since.

Why the numbers moved so fast

A quadrupling in one week is not a gradual humanitarian deterioration. It is the signature of a front line collapsing and civilians leaving ahead of it.

Displacement in Yemen has generally been incremental — families moving short distances, often repeatedly, as shelling shifts. A step change of this size indicates territory changing hands quickly enough that people are leaving in a single wave rather than over months.

It also means aid agencies are responding to a distribution of need that did not exist a fortnight ago. Stocks positioned for a static front are in the wrong places.

The Red Sea coast changes the map

Alongside the inland advance, Houthi forces took Yemen’s Red Sea coast, consolidating control over the approaches to the Bab al-Mandab Strait.

That has consequences well beyond Yemen — the strait is the southern gate to the Suez route and a corridor for Saudi oil exports, which we examined in our coverage of the fall of Mocha. But it has a humanitarian dimension too. Yemen imports the overwhelming majority of its food and fuel, and it does so through ports. Who controls the coast controls what reaches the interior, and on what terms.

What 76,000 people moving actually involves

Displacement figures are easy to read past. It is worth being concrete about what the number describes.

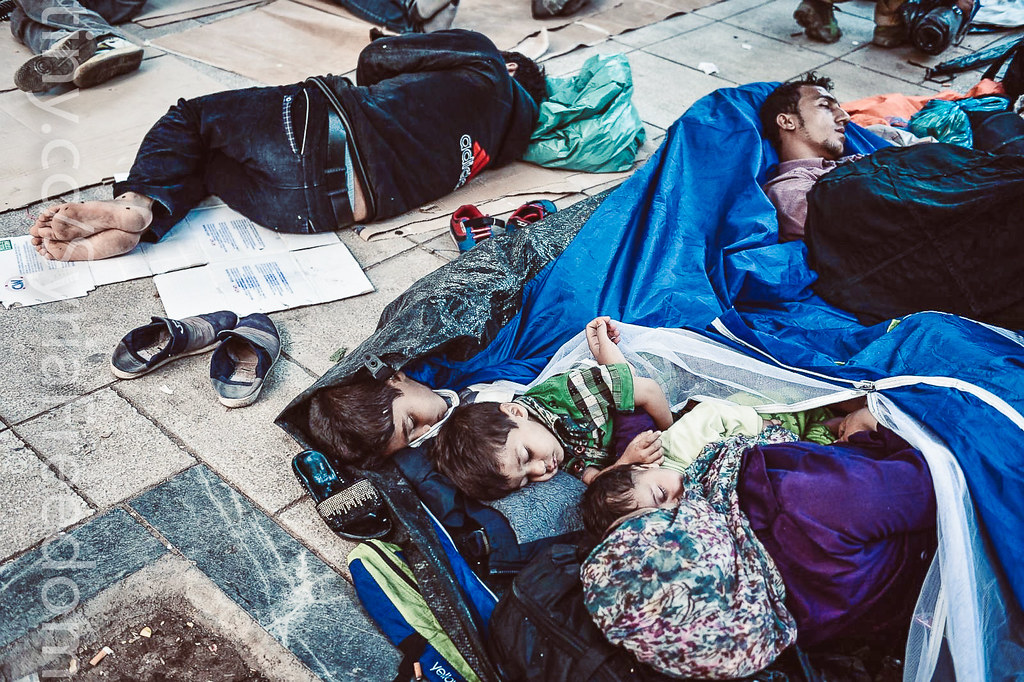
Most of those who flee move short distances — to a neighbouring district, to a relative’s house, to open ground on the edge of a town that already hosts people displaced in earlier rounds. Very few reach a formally managed camp. UPI’s report on the exodus describes families leaving with what they can carry.

The immediate needs are consistent and unglamorous: water, shelter material, cooking fuel, and cash. The medium-term problem is that host communities in Yemen have been absorbing displaced families for the better part of a decade and have very little left to share. Each new wave is landing on thinner ground than the last.

The funding problem underneath

Yemen’s aid operation has been running below requirement for years. A displacement surge of this speed lands on a system that was already rationing.

The mechanics are unglamorous and decisive: shelter materials, water trucking, and cash transfers all have procurement lead times measured in weeks. When 50,000 people move in seven days, the gap between need and delivery is filled by host communities that are themselves poor, or it is not filled.

No new funding appeal had been announced at the time of the UN’s report.

There is a structural reason Yemen struggles for attention even at moments like this. The war has run long enough to lose novelty, and it competes for the same donor budgets as more visible emergencies. Displacement figures that quadruple in a week are precisely the kind of data point that moves funding decisions — but only if they are noticed while they are current.

What determines the next month

Whether the offensive stops. If the Houthis consolidate what they have taken, displacement flattens and the response becomes a logistics problem with a known shape. If the advance continues toward Aden or further into Taiz’s remaining government-held districts, the 76,000 figure will be obsolete quickly.

Watch, too, for port access arrangements. Whether humanitarian cargo continues to move through Red Sea ports under the new control arrangement will determine whether this stays a displacement emergency or becomes a food security one.

Reader questions

How many people have been displaced in Yemen since July?

At least 76,000, according to the United Nations. The figure quadrupled during the week to 12 September.

Which area is worst affected?

Taiz province, where roughly 8,300 households — nearly 50,000 people — have been displaced from districts within the governorate.

What triggered the surge?

A large-scale Houthi offensive against Yemeni government forces launched the previous week, which has taken multiple positions and left hundreds dead.

Have the Houthis taken the Red Sea coast?

Yes. Houthi forces captured Yemen’s Red Sea coast, strengthening their control over the Bab al-Mandab Strait.

Is there a new humanitarian appeal?

No new appeal had been announced when the UN reported the displacement figures. The IOM has warned that the situation is worsening rapidly.

Why does Yemen’s coastline matter for aid?

Yemen imports most of its food and fuel through seaports. Control of the coast determines what supplies reach the interior and under what conditions.

Our continuing Yemen coverage tracks both the humanitarian situation and the shipping consequences — start with the escalation report.

Saudi East-West Pipeline Shut After Drone Strikes From Iraq

Saudi Arabia has shut down the Saudi East-West pipeline, the 1,200-kilometre artery it uses to move crude from its eastern oilfields to the Red Sea, after a series of drone attacks launched from Iraq. The closure removes the kingdom’s main insurance policy against disruption in the Gulf at precisely the moment that insurance is most needed.

CNBC reported that the shutdown was precautionary, taken after drones struck the line in the Riyadh and Medina regions on Thursday morning, starting fires and causing some damage. Riyadh has not published a damage assessment or a restart date.

Why this particular pipeline matters

The East-West line carries up to 7 million barrels per day from Abqaiq in the east to the Yanbu terminal on the Red Sea. Its entire strategic purpose is to let Saudi crude reach world markets without passing through the Strait of Hormuz.

That mattered little for most of the past decade. It matters enormously now. With the United States and Iran contesting control of Hormuz, Saudi Arabia had been leaning on the East-West route to keep exports flowing westward. Closing it narrows the kingdom’s options to the very chokepoint it was built to bypass.

The timing compounds an already tight picture. Houthi forces took Yemen’s Red Sea coast last week, tightening their grip on the Bab al-Mandab Strait at the southern end of the same sea lane — a development we covered in our report on the fall of Mocha. A tanker leaving Yanbu now sails south toward contested water.

What the attack says about the conflict’s shape

The drones came from Iraq, not Yemen. That is a meaningful shift. Attacks on Saudi energy infrastructure have historically originated from Houthi-held territory to the south; an Iraqi launch point opens a second axis and puts central Saudi Arabia — Riyadh and Medina are far inland — within reach.

No group had claimed responsibility at the time of the initial reports. Al Jazeera’s account situates the strike within the wider Iran-aligned campaign that has intensified since American strikes inside Iran, including the recent attack on Kermanshah.

It also follows Houthi strikes on the kingdom earlier in the same week, which hit energy facilities and civilian assets. The pattern that emerges is not a single spectacular attack of the kind that took Abqaiq offline in 2019, but repeated smaller strikes on dispersed targets. That is harder to defend against and harder to price, because each individual hit is survivable while the cumulative effect on operating decisions is not.

The price response

Crude broke above $100 a barrel for the first time in months, with Brent trading above $107 on Friday. Prices finished the week more than 8% higher.

Two things are worth separating here. The first is the physical loss: a closed pipeline is barrels that cannot move on a particular route, not barrels that cease to exist. The second is the risk premium: traders are pricing the possibility that the next strike hits something harder to replace. Most of the move is the second thing.

That distinction matters for how long the price holds. If the line restarts within days and no further infrastructure is hit, the premium deflates. If attacks continue on a second front, it does not.

Where the cost lands

Higher crude reaches consumers through fuel, freight and the price of anything that moves. It has already begun feeding official data — US wholesale prices rose 0.4% in August on the back of energy, as set out in our coverage of that release.

Oil-importing economies absorb the hit most directly. Countries that subsidise fuel face a widening bill on top of the import cost, which turns an energy shock into a fiscal one.

Central banks face the familiar bind. An energy-driven price rise is a supply shock, and textbook practice is to look through it. Looking through it is harder when inflation is already running above target and a second shock arrives before the first has faded.

What to watch from here

Three signals will tell you which way this resolves.

  • A restart announcement. Saudi Aramco confirming the line is back would take the sharpest edge off the premium.
  • Whether Iraq-launched attacks repeat. One strike is an incident. A pattern is a new front, and prices will treat it that way.
  • Hormuz traffic counts. With the western route closed, Gulf transit volumes become the single best read on how much Saudi crude is actually reaching buyers.

Questions readers are asking

How much oil does the East-West pipeline normally carry?

Its capacity is about 7 million barrels per day, though it typically runs well below that. Actual throughput before the shutdown has not been disclosed.

Does the shutdown mean Saudi exports have stopped?

No. It closes one route. Crude can still be exported through Gulf terminals, but those cargoes must transit the Strait of Hormuz, which is the risk the pipeline existed to avoid.

Who launched the drones?

The drones were launched from Iraq. No group had claimed responsibility in the initial reporting, and Saudi authorities have not formally attributed the attack.

Will petrol prices rise?

Pump prices follow crude with a lag of roughly two to four weeks in most markets, and the pass-through depends heavily on local taxes and any subsidy. A sustained move above $100 would show up at the pump; a brief spike may not.

How long can the pipeline stay offline?

That depends on damage the kingdom has not disclosed. Precautionary shutdowns after limited damage have historically been measured in days, but no restart timeline has been given.

For the wider picture on how this conflict is reshaping trade routes and energy prices, see our continuing coverage of Red Sea shipping and the inflation data.

Australia Just Rewrote the Line for Skilled Visas

Skilled workers hoping to move to Australia are now standing in a very different line than they were this summer. New Australia visa processing priorities took effect on July 25 under Ministerial Direction 119. The change reorders who gets processed first, and it caught some applicants and employers off guard.

Australia visa processing priorities under Direction 119

Direction 119 replaced the previous framework, known as Direction 105. It sets five processing tiers for both nomination and visa applications. The top tier covers onshore applicants in law enforcement and defence occupations. Offshore applicants in the same fields come next. Onshore healthcare, teaching and construction workers follow, then other onshore applications, then offshore applications generally (Fragomen).

Airport departures hall, where Australia visa processing priorities now determine who boards sooner

Who lost priority status under the new rules

The previous framework gave priority processing to employer-sponsored positions in designated regional areas. It also fast-tracked applications from sponsors holding Accredited Sponsor status. Neither factor carries priority weight under Direction 119. Regional employers and accredited sponsors who had grown used to faster processing now compete in the same tier as most other onshore applicants (KPMG).

Why onshore applicants now have a clear edge

One of the clearest shifts favors people already living in Australia over those applying from abroad. Onshore healthcare, teaching and construction applicants sit in the third priority tier. Most offshore applicants, regardless of occupation, sit in the lowest tier. Immigration lawyers say the change reflects a policy preference for converting existing visa holders and temporary residents into permanent skilled migrants, rather than recruiting fresh applicants from overseas.

What happens to applications already in the queue

The revised priority order applies to all applications lodged on or after July 25, 2026. It also applies to earlier applications that had not yet been finalized when the direction took effect. That means applicants who lodged months ago, under the old regional or Accredited Sponsor priority rules, may now find themselves reprocessed under the new tiers. Immigration advisors recommend affected applicants check their case status directly with the Department of Home Affairs, since processing order can shift even for applications already in the system.

For more on how immigration systems worldwide are adjusting this year, see Tamara News’ coverage of Canada’s higher study permit funds requirement and the UK’s HC 584 immigration rules changes.

How employers are adapting their sponsorship strategy

Employers who built their hiring plans around regional visa incentives are now reassessing those strategies. Some are shifting recruitment toward onshore candidates already working in Australia on temporary visas, since those applicants now clear faster under the new tiers. Others are lobbying industry groups to seek carve-outs for sectors facing acute skills shortages, though the government has not signaled plans to revisit Direction 119 in the near term.

What this means for prospective skilled migrants

Applicants weighing Australia against other skilled-migration destinations should factor processing tier into their timeline expectations, not just occupation eligibility. An offshore applicant in a non-priority occupation could now wait considerably longer than an onshore healthcare worker with an otherwise similar case. Immigration consultants recommend applicants check the current five-tier structure before lodging. Direction 119 replaced a framework that had been in place for several years, and further revisions remain possible.

How this fits Australia’s broader skills strategy

The reshuffle follows years of debate in Australia over how to balance regional development incentives against national skills shortages in healthcare, teaching and construction. Previous governments leaned on regional visa incentives to spread population growth beyond Sydney and Melbourne. Direction 119 signals a shift toward prioritizing sectors the government sees as most strained right now, even if that means deprioritizing the regional dispersal goals earlier policies were built around. Officials have not published a public rationale document beyond the direction itself, leaving much of this interpretation to immigration lawyers and industry groups tracking the change.

What to watch for next

Industry groups representing regional employers have signaled they plan to lobby for a partial rollback or a transition period for applications already committed to regional pathways before July 25. The Department of Home Affairs has not indicated a review timeline. Applicants and sponsors navigating the system in the meantime should treat Direction 119 as the current operating rules, not a temporary adjustment, since ministerial directions in Australia’s immigration system have historically remained in force for years once issued.

Frequently asked questions

  • When did the new Australia visa processing priorities take effect? July 25, 2026, under Ministerial Direction 119.
  • What replaced the old priority framework? Ministerial Direction 119 replaced Direction 105, introducing five new processing tiers.
  • Who gets top priority now? Onshore applicants in law enforcement and defence occupations, followed by their offshore counterparts.
  • Did regional visas lose their priority status? Yes. Positions in designated regional areas no longer receive priority processing under Direction 119.
  • Does the change apply to applications already lodged? Yes, it applies to applications lodged on or after July 25, 2026, and to earlier unfinalized applications.

Sources