Monthly Archives: September 2026

Banks Lent SoftBank More Than It Asked For. Shareholders Disagreed

SoftBank borrowed more than it asked for, on the same day its shares had their worst session
since July. The SoftBank OpenAI loan came in at $11.87 billion, a two-year facility from
about 20 banks, against an original $10 billion target. Bloomberg reported the terms on 14 September 2026,
citing people familiar with the arrangement. The gap between what lenders would fund and what equity
investors would tolerate is the story.

What the SoftBank OpenAI loan consists of

The facility runs for two years. Around 20 banks committed to it, and the book closed above the target
rather than below it. Oversubscription of that size signals confidence among lenders.

It joins an existing stack. SoftBank already holds a $10 billion margin loan secured against its OpenAI
shares, with Goldman Sachs and JPMorgan among the lenders. Bankers have also discussed a bond sale of up to
$20 billion.

The company said last week it would repay the remaining $25.9 billion of a $40 billion bridge loan on 15
September. Taken together, SoftBank has committed roughly $65 billion to OpenAI by October, for a stake
reported at around 13 per cent.
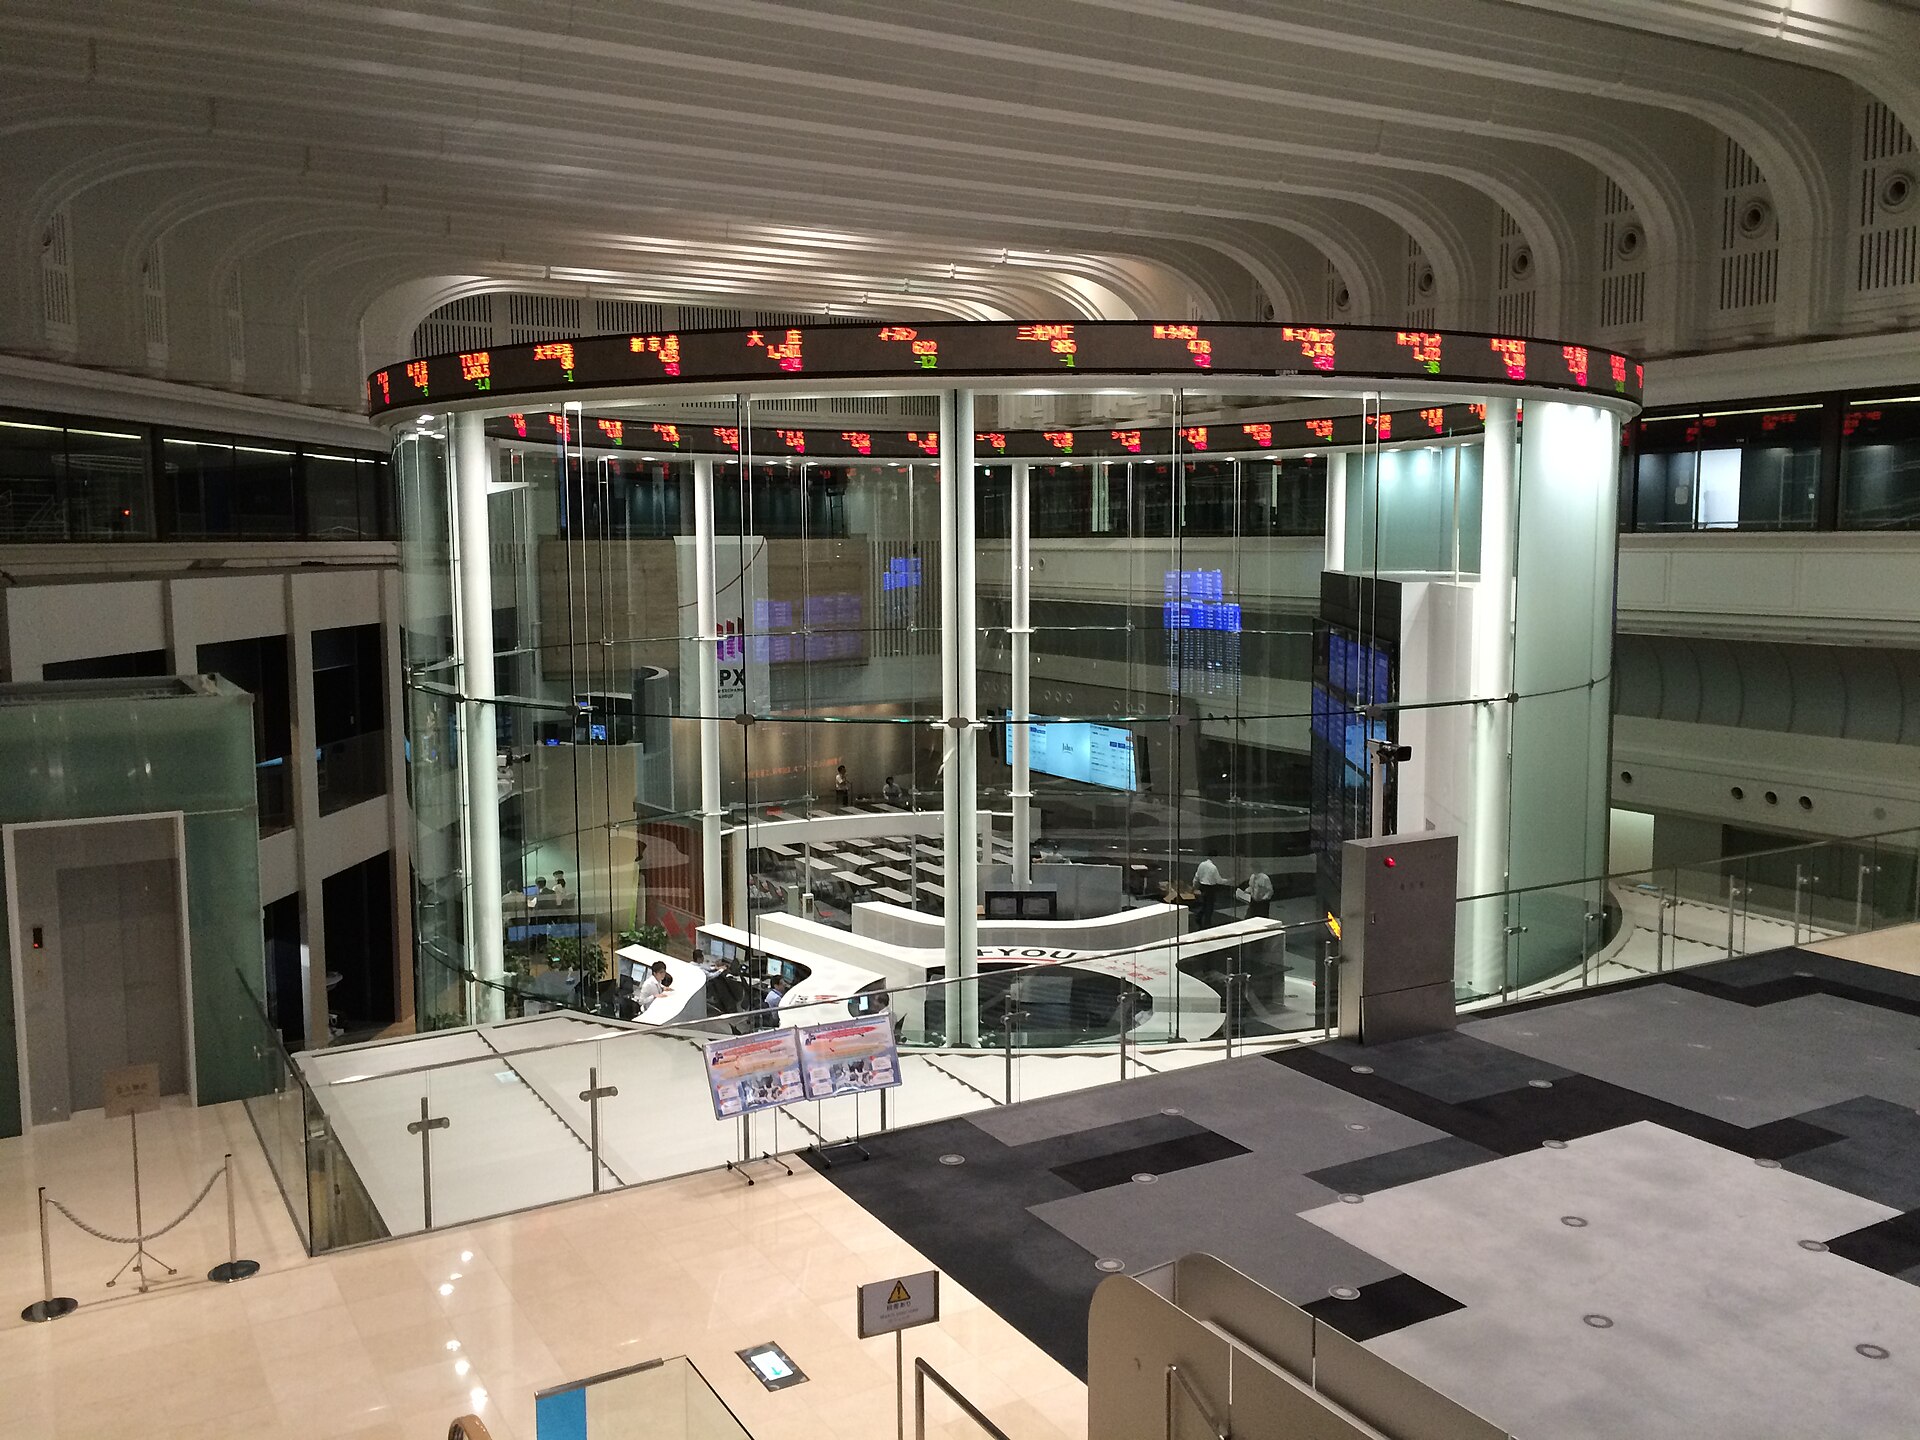
Tokyo Stock Exchange trading floor where the SoftBank OpenAI loan moved the shares
The Tokyo Stock Exchange. SoftBank shares fell as much as 13 per cent on the day the facility was reported.

Why the shares fell while the banks said yes

SoftBank stock dropped as much as 13 per cent on Monday, its steepest fall since 17 July. The trigger was
not the loan itself.

Leading AI executives spent the weekend arguing publicly for a slower pace of frontier-model development.
Markets read that as a demand signal and repriced the AI hardware and infrastructure complex. SoftBank, as
the most visible listed proxy for OpenAI exposure, took a heavier hit than most.

So two verdicts arrived on the same day. Credit markets funded the position above target. Equity markets
marked it down. We covered the underlying argument in our report on
the AI slowdown call from
Amodei, Altman and Musk
.

The leverage question the SoftBank OpenAI loan raises

Borrowing against a private stake works while the stake’s value holds. It compounds against you when the
value falls, because collateral requirements do not wait for a recovery.

Timing adds to the pressure. Sam Altman told Fortune that OpenAI will not proceed with a public offering
this year while it addresses safety concerns. An IPO is the cleanest route to liquidity for a stake of this
size. Pushing it out extends the period during which SoftBank services debt without a market price to
refinance against.

None of that makes the position unsound. It does mean SoftBank’s cost of capital becomes a variable worth
watching for anyone in the OpenAI orbit — follow-on rounds, secondary sales and listing timelines all move
with it.

There is precedent for both outcomes. SoftBank’s concentrated bets have produced its best returns and its
worst. The Alibaba stake funded two decades of expansion. The Vision Fund’s later vintages did not. A single
position this large works exactly as well as the underlying asset does.

What differs this time is the funding mix. Earlier bets leaned on fund structures with outside limited
partners sharing the downside. This one leans on debt secured against the asset itself, which keeps more of
the upside and all of the risk on SoftBank’s own balance sheet.

What it says about the AI funding cycle

Private credit is still flowing into AI infrastructure at scale. Our reports on
Positron AI’s $875 million
round
and Google’s
Finnish data-centre investment
show the same pattern in different corners of the stack.

What has changed is the divergence. Lenders and public shareholders are now pricing the same assets
differently, and they are doing it in the same week. That gap tends not to persist. One side usually moves
toward the other.

What to watch on SoftBank’s balance sheet

Three markers will show which way it resolves. First, whether the $20 billion bond sale proceeds, and at
what spread. Second, whether the margin loan against the OpenAI stake gets topped up or repriced. Third,
whether the October funding target of roughly $65 billion is met in full.

Also watch OpenAI’s own signals on timing. Any change to the listing schedule feeds straight back into
SoftBank’s refinancing options.

Questions on the financing

How large is the loan?

$11.87 billion, arranged as a two-year facility from about 20 banks, above an initial $10 billion target.

Who reported it?

Bloomberg and The Japan Times reported the terms on 14 September 2026, citing people familiar with the matter.

How much has SoftBank committed to OpenAI?

Roughly $65 billion by October, for a stake reported at around 13 per cent.

Why did the shares fall?

AI executives called publicly for slower frontier development over the weekend, and markets repriced AI-linked stocks. SoftBank fell as much as 13 per cent.

Is OpenAI planning to list this year?

Sam Altman said it would not proceed with a public offering this year while the company addresses safety concerns.

Primary sources

An AI Lab Just Quit Big Tech’s Lobby Over Three Bills on Chips

An AI company has walked out of Washington’s biggest tech trade group over three
chip export bills. Anthropic is ending its membership of the Information Technology
Industry Council, Axios reported on 8 September 2026. ITI had written to the Senate and House Armed Services
Committees urging lawmakers to strip the AI OVERWATCH Act, the Chip Security Act and the MATCH Act from this
year’s defence policy bill. Anthropic supports all three.

What the three chip export bills would do

Each measure attacks a different gap in the current export-control regime.

The AI OVERWATCH Act would require the Commerce Department to notify Congress before approving export
licences for sensitive dual-use chips destined for adversarial nations, and to allow a review period first.
That review window was shortened from two years to 18 months. ITI described 18 months as “an eternity”.

The Chip Security Act would require companies to track their AI chips, aimed at countering smuggling of
US technology. The MATCH Act would press American allies to restrict sales of chipmaking equipment to China,
slowing the growth of its domestic industry.

All three cleared the House Foreign Affairs Committee with substantial bipartisan support. They sit in
the Senate National Defense Authorization Act managers’ package, following technical assistance from the
White House.

An AI processor die, the technology behind the chip export bills split
An AI processor die. Tracking requirements in the Chip Security Act would follow hardware like this after export.

Why Anthropic broke with the group over the chip export bills

ITI’s letter argued the measures would damage American dominance in global markets. Its membership
includes Google, OpenAI and Nvidia — companies with large commercial stakes in international chip and model
sales.

An ITI spokesperson confirmed the departure, describing a “broad consensus position” among members that
the three bills should not advance in the NDAA. The spokesperson said the membership is aligned that the
bills undermine the American tech stack. Both sides here are stating their own case, and each has a
commercial interest in the outcome.

Anthropic’s position runs the other way. Chief executive Dario Amodei has argued publicly for tighter
restrictions on advanced chip exports to China. Supporters of the bills say they give existing controls the
durability they currently lack, since administrative rules can be rewritten by the next administration.

A pattern of breaking from the industry line

This is not the company’s first split from its peers. Anthropic has diverged from OpenAI and Google on
state AI safety legislation. It was also the only major lab not to directly sign a July 2026 letter
supporting open-weight models.

Trade associations work by aggregating members into a single position. That works while members share
interests. It breaks when one member’s strategy depends on rules the others are lobbying against.

The politics do not split cleanly along party lines either. Conservative groups including Heritage Action
and American Compass back the bills, alongside bipartisan congressional support. We covered the broader
safety argument inside the industry in our report on
the AI development slowdown
its own builders are asking for
, and the competitive backdrop in
China’s intelligent
computing plan
.

What the fight means outside Washington

For chipmakers, the Chip Security Act’s tracking requirement is the operational question. Following
hardware after sale means new record-keeping obligations across distributors and resellers.

For allied governments, the MATCH Act is the sensitive one. It asks other countries to restrict their own
equipment exports, which raises sovereignty objections in the Netherlands, Japan and South Korea. Our report
on the Nvidia-Groq antitrust
probe
covers the regulatory pressure building on the same companies from a different direction.

For buyers outside the United States, more licensing steps usually mean longer lead times, even where a
licence is eventually granted.

The NDAA clock now running

The Senate returned from summer recess on 14 September with the NDAA awaiting floor action. That is where
the three measures live or die.

Three signals will show which way it goes. Whether the bills survive the managers’ package intact. Whether
the 18-month review period gets stretched or trimmed in negotiation. And whether other ITI members follow
Anthropic out, which would say more about the association’s future than about the bills.

Questions about the split

Which three bills are involved?

The AI OVERWATCH Act, the Chip Security Act and the MATCH Act, all attached to this year’s National Defense Authorization Act.

Why did Anthropic leave ITI?

ITI wrote to congressional committees urging that the three bills be stripped from the defence bill. Anthropic supports them.

What does the Chip Security Act require?

It would require companies to track their AI chips, aimed at countering smuggling of US technology.

What is the MATCH Act?

A measure pushing US allies to restrict sales of chipmaking equipment to China, to slow its domestic chip industry.

Who else belongs to ITI?

Members include Google, OpenAI and Nvidia. An ITI spokesperson described a broad consensus among members against the three bills.

When will this be decided?

The Senate returned on 14 September with the NDAA awaiting floor action, so the outcome turns on that legislative process.

Reporting used

Europe Could Only Agree to Keep Its Russia Sanctions for a Week

The European Union bought itself a week. The bloc’s
Russia sanctions renewal failed to clear its usual six-month extension on 14 September
2026, so ambassadors rolled the list forward by seven days instead. The listings now run to midnight on 22
September. France and Slovakia held out over which names stay on, and the Danish presidency confirmed the
short extension after unanimity proved impossible.

How the Russia sanctions renewal stalled

The EU’s designations under its Ukraine territorial-integrity regime run in six-month blocks. Every
renewal needs all 27 member states to agree. Miss the deadline and the listings lapse automatically.

This round, agreement did not arrive. Slovakia asked for Russian businessmen Alisher Usmanov and Mikhail
Fridman to come off the list. France joined the call on Usmanov from 11 September. The remaining states
objected.

Rather than let asset freezes and travel bans expire overnight, ambassadors agreed a seven-day technical
rollover. They meet again on 22 September to attempt the full six-month renewal.

EU officials in Brussels, where the Russia sanctions renewal stalled
EU officials in Brussels. Renewal of the designations requires unanimity across all 27 member states.

What is actually covered by the listings

The regime is large. Reporting on the deadline put the number of designated individuals and entities
near 3,000, targeted with asset freezes and travel bans.

The names at the top are familiar. Vladimir Putin and Sergei Lavrov are both on the list, alongside
military commanders, officials and business figures. Below them sit companies, banks and logistics
operators.

These personal designations are separate from the EU’s sectoral measures on energy, finance and
technology. Those sit under different legal instruments and were not at risk this week. It is the individual
listings that faced the midnight deadline.

The dispute is formally about individual names rather than the policy as a whole. Each designation rests
on its own evidence file, and a member state can argue that one file is weak without rejecting the regime.
That framing matters to the two capitals holding out. It also explains why the disagreement has not been
presented as a challenge to the sanctions policy itself.

Other member states read it differently. Slovakia has pressed for a broader loosening of the bloc’s
sanctions approach on previous occasions, which colours how its requests are received in Brussels.

Why a single name can hold up the whole list

Unanimity gives every capital a veto over the package rather than over one entry. A state that wants one
designation removed can only press its case by withholding consent from everything.

That structure turns individual disputes into bloc-wide deadlines. It also hands leverage to whichever
government is willing to run the clock down, because the alternative to agreement is total lapse rather than
partial.

The wider pattern is not new. Hungary and Slovakia have both slowed previous rounds. What is new here is
France appearing on the same side of a delisting request, which changes how the dispute reads politically.
We covered an earlier expansion of the regime in our report on
the new sanctions proposed
after the Leipzig drone incident
, and the parallel deadlock at the UN in our piece on
the Iran sanctions panel
vote
.

What a lapse would actually mean

If the listings expired, frozen assets inside the EU would become accessible again. Travel bans would
stop applying. Banks and registrars would need to act on the change quickly, because holding assets frozen
without a legal basis creates its own liability.

Reversal is not symmetrical. Re-listing a delisted person takes a fresh legal act, and that person can challenge it
in the EU courts. Assets moved in the interval are hard to reach again.

That asymmetry is why even sceptical member states have generally preferred short technical extensions
over letting a deadline pass. Our coverage of
the BRICS New Delhi
declaration
sets out the counter-bloc’s position on exactly this kind of unilateral measure.

What has to happen by 22 September

Three outcomes are possible. Ambassadors agree the standard six-month renewal, with or without quiet
technical delistings. They agree another short extension, which would signal deeper deadlock. Or the list
lapses, which would be unprecedented for this regime.

Watch whether the Danish presidency revives the idea of moving to a twelve-month renewal cycle. Fewer
renewal points would mean fewer chances to hold the package hostage, which is precisely why some capitals
resist it.

Questions on the deadline

What did the EU actually extend?

The EU’s listings of individuals and entities under its Russia sanctions regime, extended by seven days to midnight on 22 September 2026.

Why only seven days?

Member states could not reach the unanimity a six-month renewal requires, so ambassadors agreed a short technical rollover instead.

Who objected?

Slovakia asked the bloc to delist Alisher Usmanov and Mikhail Fridman. France joined the request on Usmanov from 11 September.

How many people and entities are listed?

Reporting around the deadline put the figure near 3,000, subject to asset freezes and travel bans.

Are energy and banking sanctions affected?

No. Sectoral measures sit under separate legal instruments. This deadline applied to the individual and entity designations.

What happens if the list lapses?

Frozen assets in the EU would become accessible and travel bans would stop applying. Re-listing later requires a fresh legal act.

Source material

Image credit: Olnnu, via Wikimedia Commons (CC BY-SA 3.0).

A Rock in the Red Sea Just Changed Who Controls 10% of World Trade

One of the world’s busiest shipping chokepoints has changed hands. The
Bab el-Mandeb takeover finished on Friday 12 September 2026, when Houthi fighters reached
Perim Island after Yemeni government forces withdrew. The rocky island splits the narrowest part of the
strait into two shipping lanes. Holding it, together with the Red Sea coastline and the Hanish Islands,
gives the group physical control of the gateway between the Red Sea and the Indian Ocean.

What the Bab el-Mandeb takeover actually changed

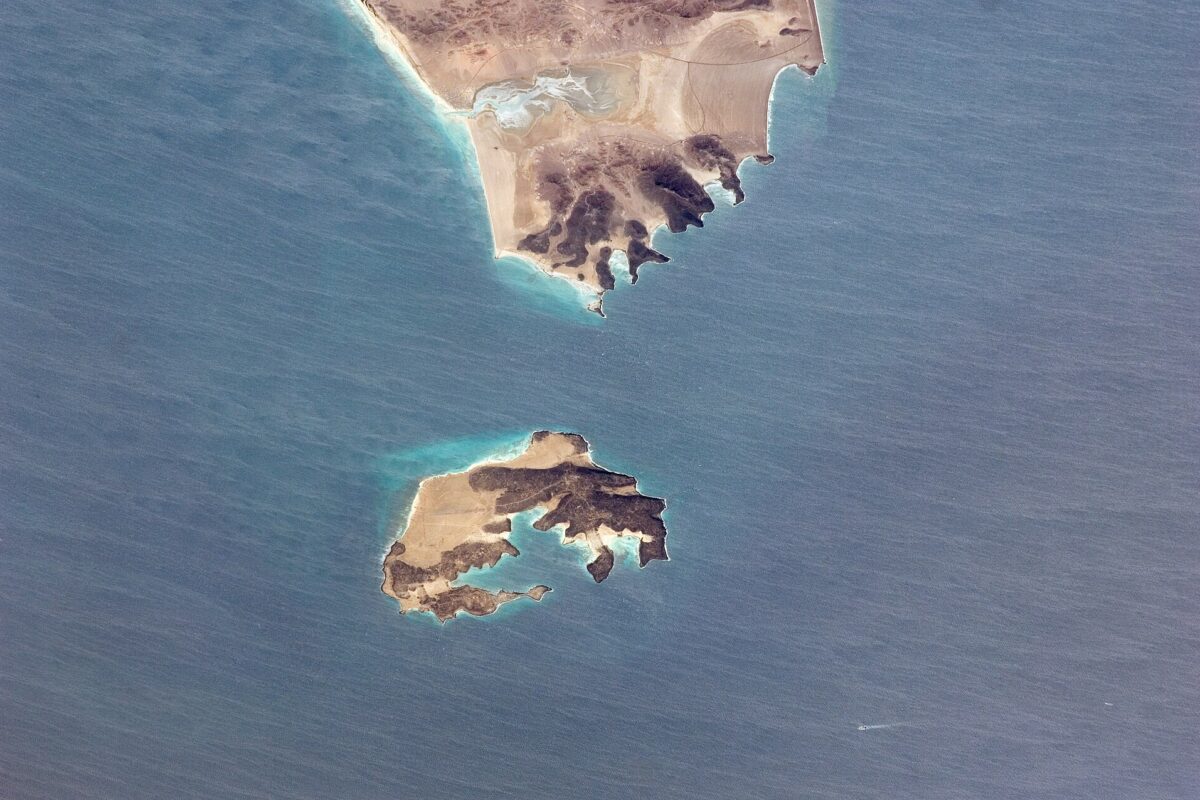
Perim, also called Mayyun, is a volcanic island of a few dozen square kilometres. Its value is position,
not size. It sits inside the strait and divides the passage into two channels.

Before last week, Houthi forces could reach shipping from the Yemeni mainland. Now they sit on both sides
of the traffic and in the middle of it. Al Jazeera reported that the group holds Yemen’s entire Red Sea
coastline alongside Perim and the Hanish Islands.

Houthi military spokesman Yahya Saree said maritime navigation remains safe for all companies except
Saudi ships. The group had already banned those. That is a statement of intent from an interested party, not
a guarantee. Shipowners will price it accordingly.

The capture came without a fight. Yemeni government forces withdrew, and the island changed hands. That
detail matters for anyone assessing how durable the position is. Ground taken without combat can be lost the
same way.

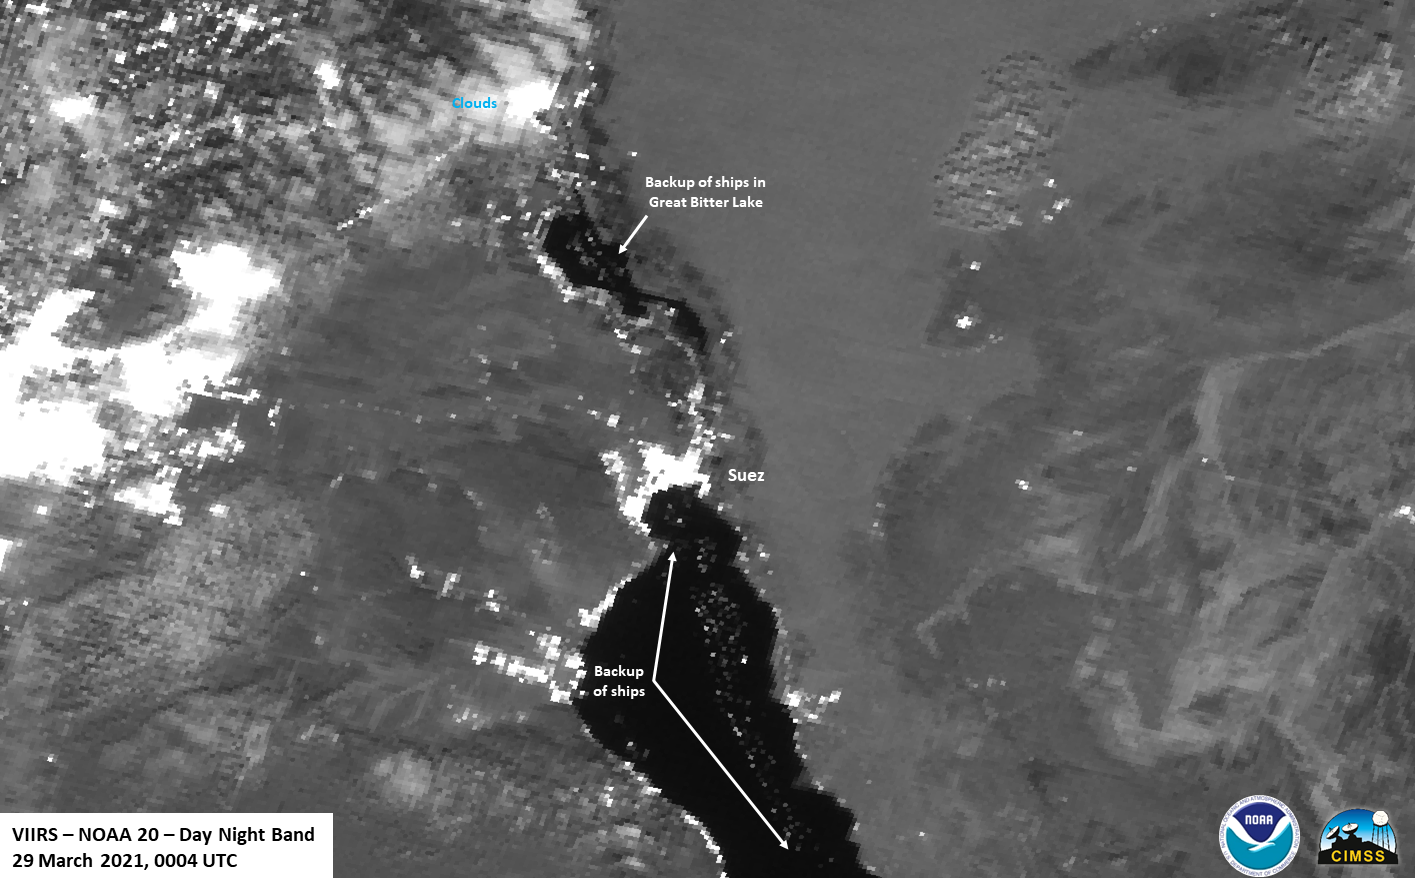
Satellite view of Red Sea shipping affected by the Bab el-Mandeb takeover
Red Sea shipping seen from orbit. Traffic through the strait feeds the Suez route to Europe.

Why this strait carries so much weight

Bab el-Mandeb connects the Red Sea to the Gulf of Aden and the Indian Ocean. Everything moving between
Asia and Europe through the Suez Canal passes it first. By Al Jazeera’s accounting the strait handles close
to 10 per cent of global trade and roughly 5 to 7 per cent of seaborne oil.

The alternative is the Cape of Good Hope. That route adds roughly ten to fourteen days on an Asia-Europe
voyage, plus the fuel to cover it. Carriers absorb some of that. They pass on the rest through surcharges.

Insurance is the faster-moving cost. War-risk premiums reprice within days of a change in control. They
reprice again after any incident. Owners often feel the insurance line before the freight line.

Schedules take the strain next. A longer route ties up more ships to run the same weekly service. Vessels
that are at sea cannot load elsewhere. Capacity tightens across unrelated trades, and rates rise on routes
that never touch the Red Sea.

Who feels the Bab el-Mandeb takeover first

Egypt feels it early. Suez Canal transit fees are a significant source of foreign currency, and traffic
that diverts around Africa never reaches the canal.

Saudi Arabia faces a narrower problem. With Saudi-linked vessels named as excluded, exports routed
through the Red Sea carry a specific risk that other flags do not. That follows the pressure already visible
after the shutdown of the
East-West pipeline
. The advance began further north, as our report on
the capture of Mocha
set out four days earlier.

East African economies sit in a different position again. Djibouti and Eritrea face the strait directly.
Port revenue, transhipment volumes and regional bunkering all depend on traffic that now passes a contested
gate.

Importers further along the chain feel it last and least precisely. A consumer-goods buyer in Europe sees
a longer lead time and a higher landed cost. There is no single line item to point to. Our earlier
reports on the oil price shock hitting
Asian economies
and the
displacement crisis inside Yemen
trace the two ends of the same conflict.

The next test for Red Sea shipping

Three signals will show whether the situation settles or deteriorates. Watch transit counts published by
the Suez Canal Authority, because diversion shows up there before it shows up in retail prices. Watch
war-risk premium quotes, which move faster than official statements. And watch whether the stated exemption
for non-Saudi shipping holds in practice over the coming weeks.

Naval escort arrangements are the other variable. Any expansion or withdrawal of escort operations would
change the calculation for owners deciding between the strait and the Cape.

Questions about the strait

Where is Bab el-Mandeb?

It is the strait between Yemen and Djibouti and Eritrea, linking the Red Sea to the Gulf of Aden and the Indian Ocean.

What is Perim Island?

A small volcanic island, also called Mayyun, that sits inside the strait and divides its narrowest part into two shipping lanes.

Is shipping through the strait now blocked?

No. Houthi spokesman Yahya Saree said navigation is safe for all companies except Saudi ships. That is the group’s own statement.

How much trade passes through?

Al Jazeera puts it near 10 per cent of global trade and roughly 5 to 7 per cent of seaborne oil shipments.

What is the alternative route?

Around the Cape of Good Hope, which adds roughly ten to fourteen days to an Asia-Europe voyage plus the extra fuel.

Where this reporting comes from

The Pentagon Finally Put Numbers on What the Iran War Cost It

The Defense Department’s inspector general has published the first formal accounting of what the
Iran war cost American forces. The Pentagon watchdog Iran report, released on Monday 14
September 2026, covers 28 February to 30 June. It tallies damage to bases across eight countries, the loss
of critical radar, and the strain on munitions stockpiles. It is the most detailed public picture of the
war’s early months so far.

What the Pentagon watchdog Iran report counted

Iranian strikes damaged or destroyed hundreds of buildings and structures at American bases, according to
the review. The affected countries span the Gulf and the wider region: Kuwait, Bahrain, Qatar, the United
Arab Emirates, Saudi Arabia, Iraq, Oman and Jordan.

Some losses mattered more than their replacement cost suggests. Missile defence radar installations were
among the assets destroyed in the war’s opening days. Radar is what turns an interceptor into a defence. Lose
the sensor and the shooter has nothing to aim at.

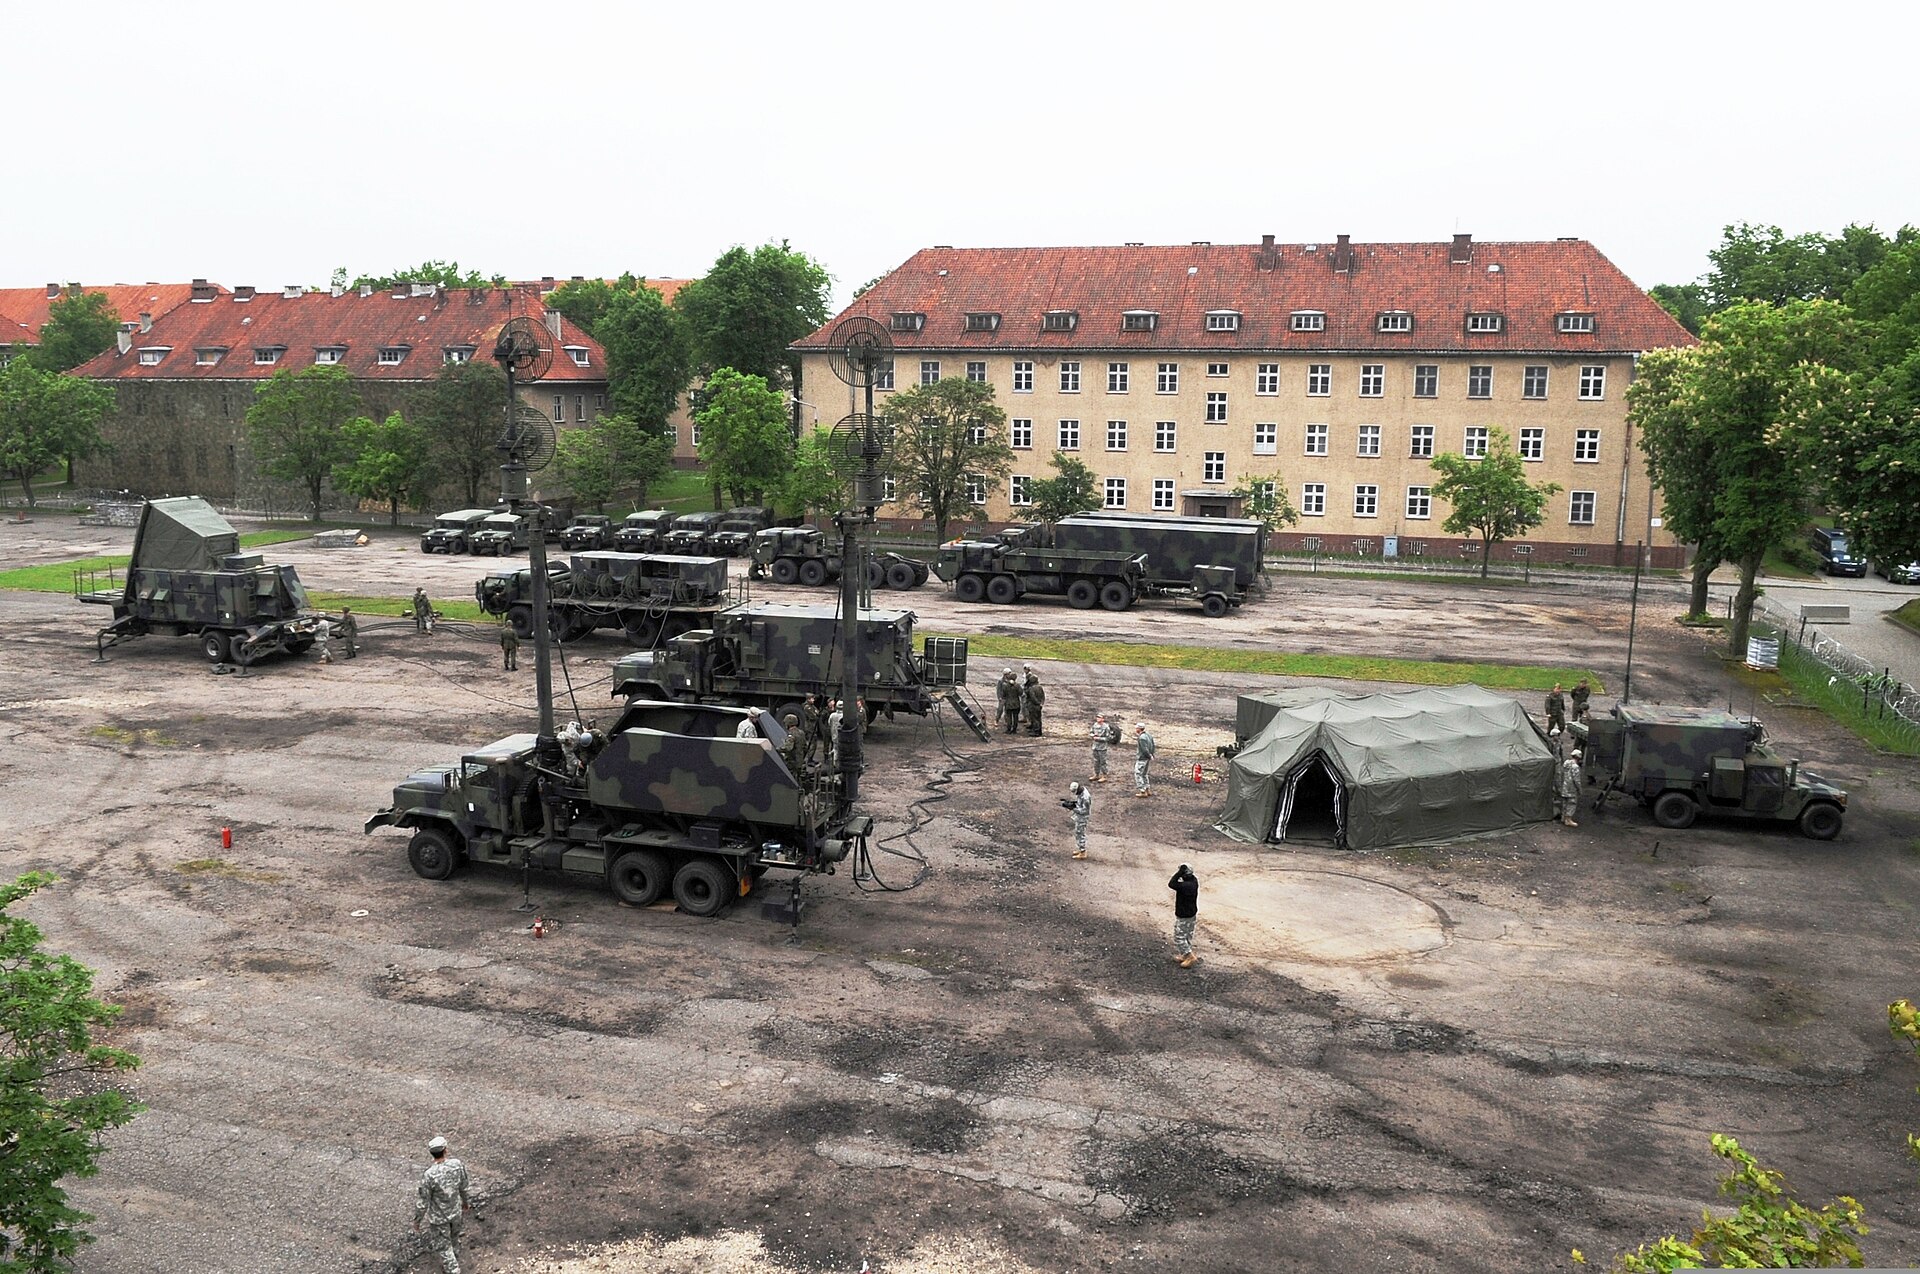
Air defence battery of the type covered in the Pentagon watchdog Iran report
A Patriot air-defence battery. The watchdog review found radar installations among the earliest losses.

Why losing Bahrain reshaped the naval map

The destruction of the Navy’s regional hub in Bahrain forced an improvisation. With the hub gone, the
Navy struggled to establish adequate bases and support ports in the region.

Diego Garcia took up much of the load. The British Indian Ocean Territory atoll sits roughly 2,400 nautical
miles from the Gulf. Using it as a sea logistics hub stretched resupply cycles to between 14 and 18 days.
That is a long time for a ship waiting on parts, fuel or ordnance.

Distance is not a footnote in naval operations. It sets how often a ship can be on station, how quickly a
damaged vessel returns to service, and how much of the fleet is in transit rather than in position.

The munitions question the review reopens

The report acknowledges depletion of key munition stockpiles. That is a notable admission, because the
Pentagon has repeatedly pushed back against reporting of a shortage. Defence officials have said the
military has every weapon it needs to fight any conflict.

Both statements can be technically true at once. A stockpile can fall sharply and still exceed the level
planners consider adequate. The gap between the two positions is a judgement about how much margin is
enough, not a dispute about arithmetic. Readers should note that the Pentagon’s position here is the
Pentagon’s own account of its readiness.

What the review does not settle is replacement time. Interceptors and precision munitions have long
production lead times. A stockpile drawn down over four months can take years to rebuild.

Production capacity is the constraint, not budget. Advanced interceptors need specialised solid-rocket
motors and seeker components from a small supplier base. Adding a production line takes years of tooling and
qualification. Money released today shows up as delivered rounds well after the crisis that prompted it.

What the findings mean for eight host governments

The report names the countries where American bases took damage. That list is diplomatically sensitive.
Several of those governments have discussed the strikes only in general terms at home.

Basing arrangements rest on a bargain. The host provides territory and access. The guest provides
security and, usually, economic benefit. A public accounting of damage tests both halves of that bargain in
front of domestic audiences.

Expect the review to surface in parliamentary questions and local reporting across the Gulf. It gives
critics of the basing arrangements a document to cite, and it gives governments a reason to press for
clearer defensive commitments before the next round of negotiations.

What the accounting signals beyond the Gulf

The findings land while the region is still unsettled. Energy markets remain sensitive to anything that
touches Gulf infrastructure, as our reports on
the shutdown of the Saudi
East-West pipeline
and the oil
price shock reaching Asian economies
set out. The diplomatic track is unsettled too — see our coverage of
the Iran sanctions panel
vote
.

For the eight host countries, the review is also a domestic political document. It puts numbers on damage
that governments in Kuwait, Bahrain and Qatar have discussed only in general terms.

The questions the report leaves open

The review stops at 30 June. Anything after that date falls outside it, so the current state of the bases
is not covered. Expect follow-up reviews, and expect congressional committees to ask for the classified
annexes.

Three questions will shape the next round. How long will radar and air-defence replacement take? What
does the Bahrain hub’s loss mean for permanent basing decisions? And will the munitions finding change
procurement budgets in the next request to Congress?

Reader questions on the report

Who wrote the report?

The Defense Department’s inspector general, the Pentagon’s own internal watchdog, in a special report released on 14 September 2026.

What period does it cover?

From the start of the war on 28 February through 30 June 2026. Later events fall outside its scope.

Which countries had bases damaged?

Kuwait, Bahrain, Qatar, the United Arab Emirates, Saudi Arabia, Iraq, Oman and Jordan.

Does the Pentagon accept there is a munitions shortage?

The report acknowledges stockpile depletion. The Pentagon has separately said it has the weapons it needs for any conflict.

Why does Diego Garcia matter?

It became a sea logistics hub after the Bahrain naval hub was destroyed, stretching resupply cycles to 14 to 18 days.

Reporting sources