A $1.65 Billion Deal Just Reshaped Cancer Treatment’s Supply Chain

Australia’s Telix Pharmaceuticals agreed this week to buy Germany’s ITM Isotope Technologies Munich in a deal worth $1.65 billion upfront, one of the largest transactions yet in a radiopharmaceutical sector that has drawn heavy dealmaking interest in 2026. The Telix ITM acquisition deal could grow to as much as $2.35 billion including milestone payments, and it hands Telix a manufacturing and distribution network that reaches more than 65 countries.

Inside the Telix ITM acquisition deal

Telix will acquire all of ITM’s shares for $1.65 billion upfront, structured as $1.25 billion in Telix stock, $302 million in assumed net debt, and $96 million covering management equity rollovers and transaction expenses. On top of that, Telix could pay up to $700 million more in milestone payments tied to regulatory approvals, including US Food and Drug Administration clearance for ITM’s lead radiopharmaceutical asset. Telix is also taking on more than $300 million of ITM’s existing debt as part of the closing. Both boards have already approved the transaction, leaving customary regulatory sign-off as the main remaining step before the deal can be finalized.

What ITM brings to the table

ITM’s flagship candidate is ITM-11, a lutetium-177-based peptide receptor radionuclide therapy aimed at gastroenteropancreatic neuroendocrine tumors, a rare and difficult-to-treat form of cancer. The drug has completed its Phase 3 COMPETE trial, and a second Phase 3 study, COMPOSE, is fully enrolled with an interim analysis expected in the first half of 2027. ITM’s manufacturing infrastructure and distribution network covering more than 65 countries was central to Telix’s rationale for the deal.

Why this counts as radiopharma consolidation

The transaction is part of a broader wave of dealmaking in radiopharmaceuticals this year, as larger companies race to secure manufacturing capacity and late-stage pipeline assets rather than build them from scratch. Telix has described the combined company as a “vertically integrated radiopharmaceutical company,” language that signals an intent to control everything from isotope production to distribution rather than relying on partners at each stage.
Telix ITM acquisition deal

What happens before the deal closes

Telix and ITM expect to close the transaction by the end of 2026, with Telix shareholders set to hold about 76.3% of the combined company and ITM’s backers holding roughly 23.7%. The combined entity is projected to generate more than $1.3 billion in unaudited revenue and income this year, a scale that puts it in direct competition with larger players already established in nuclear medicine.

How the deal was structured to limit dilution

Telix’s decision to fund most of the upfront payment in its own stock, rather than cash or new debt, was a deliberate choice to preserve balance-sheet flexibility while still meeting ITM shareholders’ price expectations. The $302 million in assumed net debt and $96 million covering equity rollovers and transaction costs round out a structure that leaves Telix with room to continue funding its existing commercial pipeline without a major capital raise. Analysts noted that the roughly 76.3%-23.7% post-close ownership split gives ITM’s existing investors meaningful upside if the combined company’s stock performs well, an arrangement that made the deal easier to negotiate than an all-cash buyout might have been.

Why radiopharma consolidation is accelerating in 2026

Radiopharmaceuticals sit at an unusual intersection of nuclear physics, oncology and complex cold-chain logistics, since many of the isotopes involved decay within days and must move from production facility to hospital on tight schedules. That complexity has made manufacturing scale and distribution networks, rather than just drug pipelines, a competitive advantage in their own right, which helps explain why larger players have increasingly chosen to acquire established manufacturers like ITM rather than build equivalent infrastructure from scratch. Novartis and other established nuclear medicine players have made similar moves in recent years, and Telix’s acquisition of ITM is widely read as a direct response to that competitive pressure.

What analysts are watching next

Investor reaction to the announcement was mixed in early trading, with some analysts flagging integration risk given the scale of the combination, while others highlighted the strategic logic of pairing Telix’s existing commercial products with ITM’s manufacturing depth. The interim analysis of ITM’s COMPOSE trial, expected in the first half of 2027, will be an early test of whether the acquired pipeline delivers on its promise, and regulators in multiple jurisdictions will need to sign off before the companies can finalize the transaction as planned.

Frequently Asked Questions

How much is the Telix ITM acquisition deal worth?

Telix Pharmaceuticals is paying $1.65 billion upfront for Germany’s ITM Isotope Technologies Munich, with up to $700 million more in milestone payments tied to regulatory approvals.

What does ITM make?

ITM’s lead asset is ITM-11, a lutetium-177-based radiopharmaceutical designed to treat gastroenteropancreatic neuroendocrine tumors, a rare form of cancer.

How is the deal being paid for?

The upfront payment combines $1.25 billion in Telix shares, $302 million in assumed net debt, and $96 million covering management equity rollovers and transaction costs.

When is the deal expected to close?

Telix and ITM expect to close the transaction by the end of 2026, subject to standard regulatory approvals.

Who will own the combined company?

Telix shareholders will hold about 76.3% of the combined entity, with ITM’s existing backers holding roughly 23.7%.

Related coverage on Tamara News

For more context, see our reporting on Nscale ipo filing and Dangote refinery ipo.

Sources

The Fed Just Raised Rates for the First Time Since 2023 — Here’s Why

The Federal Reserve raised its benchmark interest rate for the first time since 2023 on September 16, 2026, lifting the target range by 25 basis points to 3.75%-4.00%. The Fed interest rate hike passed the Federal Open Market Committee unanimously, 12-0, and the committee’s statement made clear the move was about inflation that has not cooled as fast as policymakers hoped.

Why the Fed interest rate hike happened now

The FOMC’s statement was blunt: “Inflation remains elevated,” and the committee said “today’s policy action will support a timelier return to the Committee’s 2 percent goal.” Recent inflation readings had stayed stubbornly above the Fed’s long-term target, pushing officials to reverse course after a period of holding rates steady. The unanimous vote signaled there was little internal disagreement about the need to act, even though a rate increase carries political risk heading into a period of slower growth. Committee members had debated for months whether elevated inflation was transitory or structural, and September’s data appears to have settled that internal argument decisively in favor of tightening.

What markets are pricing in next

Investors are now pricing in one more 25 basis point increase before the end of 2026, with Fed officials’ own year-end projections ranging between 4.1% and 4.4%. That would mark the fastest pace of tightening in several years and puts the Fed ahead of, rather than behind, some of its global peers for the first time in this cycle.

The Fed is not moving alone

The European Central Bank and the Bank of Japan have already raised rates earlier in 2026, and markets widely expect the Bank of England and the Bank of Canada to follow with their own increases. The synchronized tightening reflects a shared diagnosis among major central banks: inflation pressures tied to energy costs, AI-driven capital spending and tight labor markets have proven more persistent than forecasters expected a year ago.

Fed interest rate hike

What higher rates mean for borrowers and markets

A higher federal funds rate feeds through to mortgage rates, credit card costs and corporate borrowing almost immediately, and equity markets have been volatile in the days since the decision as investors reprice growth stocks against a higher cost of capital. Companies carrying heavy debt loads, from airlines to retailers already flagging softer consumer demand, are likely to face tighter refinancing conditions into 2027.

The inflation numbers behind the decision

The Fed’s own preferred inflation gauge has stayed above its 2% target for longer than officials expected earlier this year, driven in part by energy costs and heavy corporate spending tied to AI infrastructure buildouts across the economy. That persistence is what tipped the committee toward raising rates rather than holding steady, even though growth data has shown signs of cooling in several sectors. Fed Chair statements accompanying the decision emphasized that policymakers see the current inflation trajectory as unacceptable to leave unaddressed, even at the cost of tighter financial conditions heading into next year.

How households will feel the decision first

Mortgage rates typically move within days of a Fed decision, and lenders had already priced in much of the September increase ahead of the formal announcement, meaning the sharpest impact may land on borrowers renewing adjustable-rate loans or applying for new credit in the coming weeks. Credit card issuers, whose rates are frequently pegged directly to the federal funds rate, are expected to pass the increase through to cardholders on their next statement cycle. For savers, the flip side is that yields on savings accounts and short-term Treasury instruments are also likely to tick higher, a small offsetting benefit for households sitting on cash.

How this compares with the last tightening cycle

The Fed had held its benchmark rate steady or cut it in the years following its last major tightening cycle, making this reversal notable to economists who had assumed the central bank was done raising rates for this cycle. Some analysts have described the move as an acknowledgment that earlier rate cuts eased financial conditions too quickly, allowing inflation pressures to rebuild faster than policymakers anticipated. Whether the Fed needed one hike or several to fully address that miscalculation is now the central debate among economists watching the remaining meetings this year.

Frequently Asked Questions

How big was the Fed interest rate hike?

The Federal Open Market Committee raised the target range by 25 basis points to 3.75%-4.00% on September 16, 2026, in a unanimous 12-0 vote.

Why did the Fed raise rates instead of cutting them?

The committee said inflation remains elevated above its 2% goal, and it judged that raising rates would support a timelier return to that target.

Is this the first rate change since 2023?

It is the first rate increase since 2023; the Fed had held or cut rates in the years between as it balanced inflation against growth concerns.

Are more rate hikes expected in 2026?

Markets are currently pricing in one more 25 basis point increase before year-end, with Fed officials’ own projections ranging between 4.1% and 4.4%.

Are other central banks moving in the same direction?

Yes. The European Central Bank and the Bank of Japan have already raised rates in 2026, and investors expect the Bank of England and Bank of Canada to follow.

Related coverage on Tamara News

For more context, see our reporting on Stock market ai trade rally and Lululemon cuts full year forecast.

Sources

Chipmakers Are Rallying Again — And It’s Not About Earnings This Time

Asian and US stocks climbed this week as falling oil prices and easing Treasury yields lifted risk appetite across markets. The stock market AI trade rally centered on chipmakers. This gained ground as investors bet that easing Middle East tensions would remove one of the biggest overhangs on tech valuations this quarter.

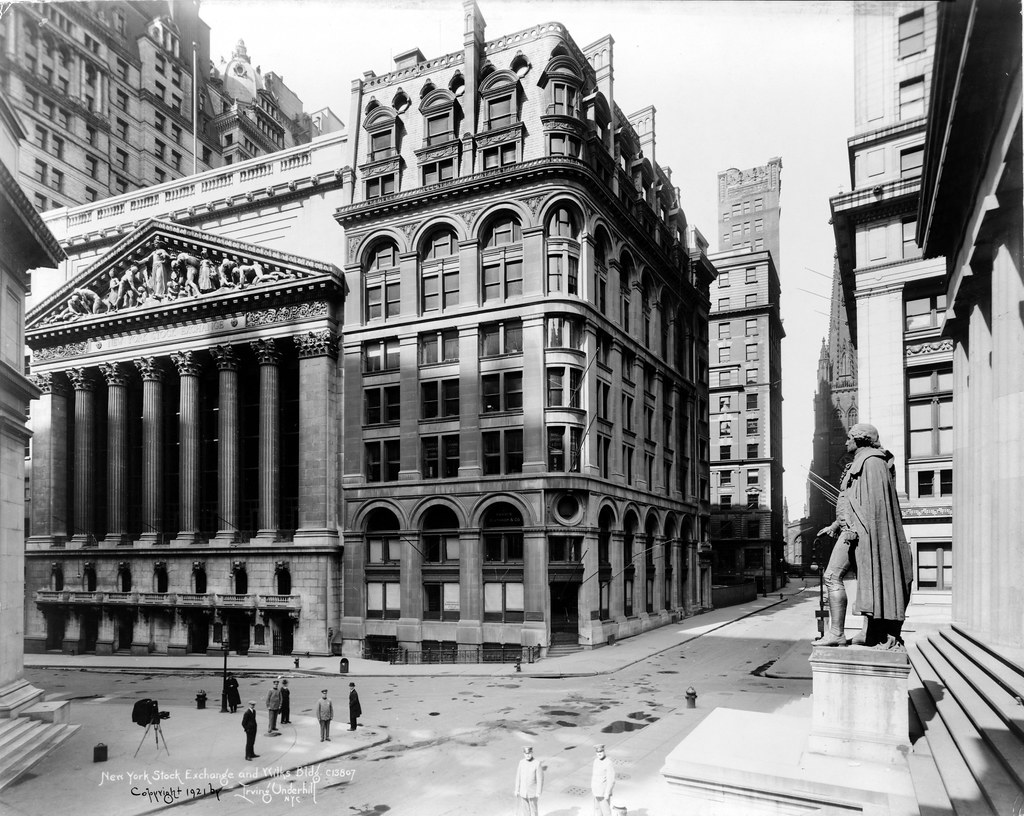
New York Stock Exchange building during the stock market AI trade rally

What’s fueling the stock market AI trade rally

The rally followed a familiar pattern this year: geopolitical relief translating directly into tech-sector buying. As oil prices fell and hopes rose for diplomatic progress in the Iran war. Asian markets were poised to extend a tech-fueled rally that began on Wall Street. Chipmakers led the move. Recovering ground lost during weeks when war-risk pricing weighed on the sector regardless of company-specific fundamentals.

The timing matters. This rally comes just days after the Federal Reserve’s first rate hike since 2023. A move that in isolation would typically pressure growth stocks like chipmakers. Instead, the geopolitical relief trade has, for now, outweighed the rate-hike drag.

How this fits the AI trade’s rough September

Chipmakers had a mixed month before this rally. Broadcom lost ground after investors reacted negatively to its fourth-quarter revenue forecast. Even though the company had beaten earnings estimates. Nvidia, meanwhile, made its second-biggest acquisition of the year, a deal for Hugging Face. Showing the AI infrastructure buildout continuing even as individual stock reactions stayed choppy. The current rally suggests investors are separating company-specific earnings jitters from the sector-wide war-risk discount that had been dragging on chip valuations broadly.

Nvidia’s Hugging Face acquisition offers a useful contrast. The deal itself was announced before this week’s rally began. Yet Nvidia shares moved with the broader chip sector rather than trading independently on the acquisition’s own merits. That pattern, where sector-wide sentiment overwhelms company-specific news. Has been a defining feature of chip stock behavior since the war escalated. And it is part of why individual earnings beats or misses have mattered less than usual this quarter.

Why bond yields matter to this story

Falling Treasury yields did as much work as oil prices in this rally. Higher yields make future tech earnings worth less in today’s dollars. This is part of why growth stocks sold off when yields hit a 20-month high earlier this month. The reversal in yields alongside the oil-price drop created a rare double tailwind for the sector. One that traders are treating as a bet on Iran de-escalation rather than a shift in underlying AI demand.

Fixed-income strategists note that this kind of dual tailwind. Falling yields and falling oil together, is unusual outside of a clear recession signal. This is not what’s happening here. Instead, both moves trace back to the same single catalyst: reduced war-risk pricing. That makes this rally more fragile than a typical yield-driven rotation into growth stocks. That is because it depends on a diplomatic outcome rather than a change in underlying economic fundamentals like inflation or employment data.

Portfolio managers who lived through the April and July collapses of earlier ceasefire attempts say they are treating this rally more cautiously than the headline gains suggest. Keeping hedges in place even while adding to chip positions. That mixed positioning, buying the rally while hedging against its reversal. Reflects a market that has learned not to fully trust Iran de-escalation headlines until a signed agreement actually holds for more than a few weeks.

Retail investors have piled into chip-sector exchange-traded funds during the rally at a faster pace than institutional flows would typically suggest is warranted this early in a diplomatic process. That is according to fund-flow data tracked by several market research desks. That gap between retail enthusiasm and institutional caution has, in prior rallies tied to this conflict. Tended to widen just before a reversal. Making it one more signal worth watching alongside the underlying ceasefire talks themselves.

What happens next for the AI trade

The rally’s durability depends heavily on whether the current round of ceasefire diplomacy holds. Prior diplomatic tracks between the US and Iran broke down within weeks in both April and July. Each time reversing the market optimism that preceded them. Investors watching the chip sector are treating this as a geopolitics trade first and an earnings trade second. That means any new incident near the Strait of Hormuz could unwind the gains as quickly as they appeared.

Frequently asked questions

What’s driving the stock market AI trade rally?
Falling oil prices and easing Treasury yields, both tied to hopes for Iran war de-escalation, are lifting chipmaker stocks this week.

Did the Fed’s rate hike hurt the rally?
The Fed raised rates for the first time since 2023 just days earlier, which would typically pressure growth stocks, but geopolitical relief has outweighed that drag so far.

How did Broadcom and Nvidia factor in?
Broadcom fell on a soft revenue forecast despite beating earnings, while Nvidia made a major acquisition of Hugging Face, showing mixed company-specific signals within the broader rally.

Why do bond yields matter to chip stocks?
Higher yields reduce the present value of future tech earnings, so falling yields alongside falling oil prices created an unusually strong tailwind for the sector.

Could this rally reverse quickly?
Yes. Prior Iran diplomatic tracks collapsed within weeks in April and July, and a new incident near the Strait of Hormuz could unwind the gains just as fast.

Related coverage

Sources

Oil Just Had Its Worst Week in Months — Here’s the Iran Angle Nobody’s Pricing In

Crude oil fell to $95.59 a barrel on 21 September, down more than 9% over four sessions. As traders bet on de-escalation in the Middle East. The drop in oil prices Iran war fears reflects a sharp reversal from earlier weeks. When the same conflict pushed prices higher. West Texas Intermediate held near $96 a barrel while Brent settled above $100.

Crude oil barrels stacked as oil prices Iran war fears ease

What’s driving the oil prices Iran war fears reversal

The decline followed reports that President Trump had decided against bombing Yemen for now and signaled openness to diplomacy with Iran. That single signal did more to move the market than weeks of supply data. Oil traders have spent months treating this conflict as a one-way risk to prices. The past few sessions show that assumption can break just as fast as it formed.

The move also lines up with the broader diplomatic push described in this outlet’s separate coverage of Qatar- and Pakistan-mediated ceasefire talks. When mediators report progress, oil desks react within hours, well before any formal agreement is signed.

Why Saudi supply data tells a different story

Despite the price drop, actual oil supply has not eased in a straightforward way. Satellite data reviewed by energy trackers shows Saudi Arabia’s observed loadings from inside the Persian Gulf jumping in recent days. A sign the kingdom is shifting exports back toward the Strait of Hormuz after a cross-country pipeline shutdown. That pipeline had rerouted Saudi barrels away from the strait during the worst of the fighting. Its return to service suggests Riyadh, at least, is positioning for calmer waters ahead. Even if a formal ceasefire has not been signed.

Traders parsing the satellite data note a distinction worth watching. Rising loadings do not necessarily mean rising total output. Saudi Arabia may simply be redistributing existing production toward its traditional export route rather than pumping more crude overall. That nuance matters for anyone trying to read supply signals directly off tanker movements. That is because a shift in routing can look identical to a genuine supply increase on a single day’s satellite pass.

How this compares with the earlier price surge

Just weeks ago, this outlet reported bond yields hitting a 20-month high as markets absorbed the shock of the war’s escalation. With oil prices surging in tandem. OPEC+ held production steady through that period and prices kept climbing anyway, driven by fear rather than fundamentals. The current reversal shows how much of the earlier surge was a war-risk premium rather than a genuine supply shortage. Strip out the fear, and the barrel count tells a calmer story.

That earlier surge also pushed gold to safe-haven buying. A pattern that has partly reversed alongside oil this week as investors rotate back toward riskier assets. The correlation between oil, gold and equity markets during this war has been unusually tight. Reflecting how much of this year’s broader market behavior has been driven by a single geopolitical conflict rather than the usual mix of independent economic signals.

Commodity strategists caution that this kind of single-catalyst market has real risks for investors trying to build a diversified portfolio. When oil, gold, bonds and equities all move in lockstep around one geopolitical storyline. The usual diversification benefits of holding a mix of asset classes weaken considerably. That has left some portfolio managers treating Iran headlines almost like a standalone macro indicator this year. Checking war-risk news before checking traditional economic releases.

Airlines and shipping companies that hedge fuel costs months in advance face a different challenge entirely. A sudden four-session drop can leave a hedged buyer paying above-market rates for weeks. Even so, spot prices fall around them. Several regional carriers have already flagged the swing in their investor communications, a reminder that volatility itself. Not just the direction of prices. Carries a real cost for businesses that depend on fuel as a major line item.

What happens next for oil markets

Analysts caution against reading too much into a four-session slide. The same diplomatic track that triggered this drop has broken down twice before. In April and again in July, each time sending prices back up within days. Traders are watching the Qatar-Pakistan mediation closely, along with any fresh incident near the Strait of Hormuz. This has been the single biggest price catalyst throughout the war. A confirmed interim ceasefire would likely extend the current slide. A new tanker incident would likely reverse it just as quickly.

Frequently asked questions

How far have oil prices fallen?
Crude fell to $95.59 a barrel on 21 September, down more than 9% over the previous four trading sessions.

What caused the sudden drop?
Reports that President Trump decided against bombing Yemen and signaled openness to diplomacy with Iran triggered the reversal.

Has oil supply actually increased?
Satellite data shows Saudi Arabia’s Gulf loadings rising as it shifts exports back toward the Strait of Hormuz, but the picture is mixed rather than a clean supply increase.

Why did oil prices rise earlier in the war?
Fear of a wider conflict and disruption to the Strait of Hormuz pushed prices up even as OPEC+ held production steady, reflecting a war-risk premium rather than a shortage.

Could prices rise again quickly?
Yes. Previous diplomatic tracks broke down in April and July, each time sending prices back up within days of a new incident.

Related coverage

Sources

Four People Are Suing Anthropic, OpenAI, Google and SpaceXAI — For Agreeing to Slow Down

Four paying subscribers to leading AI chatbots have filed a federal antitrust lawsuit against Anthropic. OpenAI, Google and SpaceXAI. This AI antitrust lawsuit makes an unusual claim: the companies agreed to slow down their own technology. And that agreement broke the law. The case, filed last week, argues the pact reduced the value subscribers get from their paid plans.

AI server data center at the center of the AI antitrust lawsuit

What triggered the AI antitrust lawsuit

The dispute traces back to 12 September. When Anthropic chief executive Dario Amodei published an essay urging leading AI firms to cooperate on slowing the pace of capability advances. Amodei framed it as a safety measure. His plan, sometimes called “pacing the frontier,” called for outside evaluators embedded inside AI companies and a shared. Industry-wide agreement on safety benchmarks and how fast capabilities should be allowed to advance.

On the same day, OpenAI chief executive Sam Altman, SpaceXAI chief executive Elon Musk. And google DeepMind co-founder Demis Hassabis each responded in public support. That coordinated agreement is now the basis of the lawsuit. The plaintiffs argue the four firms improperly restrained the pace of their own technology’s progress. This they say violates federal antitrust law.

The plaintiffs’ central argument

According to court filings reported by CNN and CBS News. The four subscribers claim the slowdown pact undermines the value they receive from their paid subscriptions. Legal filings allege that industry-wide coordination on capability pacing began months before Amodei’s public essay. That means the September statements may have been a public confirmation of private discussions rather than the start of the agreement itself.

Altman has since said OpenAI would welcome a consistent federal safety framework. But he added that the company did not believe it needed to wait for an antitrust waiver or new legislation before adopting new safety practices on its own. That response suggests the four companies may not present a unified defense as the case proceeds.

Why “safety cooperation” and antitrust law collide

Amodei’s original proposal included a request. He suggested the US government grant AI companies a restricted waiver specifically permitting safety-related discussions that would otherwise raise competition concerns. That request itself is a tell. Ordinarily, competitors coordinating on output, pricing, or the pace of product development invites antitrust scrutiny. This holds regardless of the stated motive. Whether “capability pacing” counts as a legitimate safety measure or an anticompetitive restraint on trade is now a question for the courts rather than the companies themselves.

Legal scholars who study antitrust law say the case sits in genuinely unsettled territory. Companies routinely coordinate on safety standards in other industries, from aviation to pharmaceuticals. Without triggering antitrust liability, provided the coordination does not extend to output or pricing. The plaintiffs’ argument is that slowing capability development functions economically like restraining output. That is because capability improvements are effectively the product AI subscribers are paying for. Whether a court accepts that framing will likely determine how the case proceeds from here.

What happens next for the four AI companies

None of the four companies has yet filed a formal response in court. The case adds a new front to a year that already saw Anthropic sued separately by Sony and Warner over AI music training. And increased federal attention on chip export rules and frontier model safety commitments. Antitrust cases against technology companies often take years to resolve. But early procedural rulings on whether the “pacing the frontier” agreement counts as coordination among competitors could shape how AI firms discuss safety cooperation going forward.

The broader industry is watching closely, too. If courts side with the plaintiffs. Any future joint safety statement from competing AI labs could become a liability risk rather than a public-relations win. That would push safety coordination toward government-brokered frameworks, the kind of arrangement Amodei originally asked for. It is not informal agreements announced through public essays and social media posts.

Consumer advocacy groups have taken a different view of the case, arguing that regardless of the antitrust technicalities. The lawsuit surfaces a legitimate question about who gets to decide how fast AI capabilities advance. Subscribers, the argument goes, are paying for continuous improvement. And a private agreement among four companies to slow that improvement was never put to a vote or a public comment process. Whether that framing carries any legal weight is separate from whether it resonates politically. And early commentary suggests it already has.

Frequently asked questions

Who filed the AI antitrust lawsuit?
Four paying subscribers to AI chatbot services filed the suit against Anthropic, OpenAI, Google and SpaceXAI.

What is “pacing the frontier”?
It is Dario Amodei’s proposal for AI companies to coordinate on slowing capability advances, using outside evaluators and shared safety benchmarks.

Why do the plaintiffs say this violates antitrust law?
They argue the companies improperly agreed to restrain the pace of their technology, which reduced the value subscribers receive from paid plans.

Did all four companies support the slowdown plan?
Altman, Musk and Hassabis each publicly responded in support of Amodei’s proposal on 12 September, though Altman later said OpenAI would not wait for legal cover to adopt new safety practices.

Has any company responded formally to the lawsuit?
No formal court response had been filed by any of the four companies as of this report.

Related coverage

Sources